

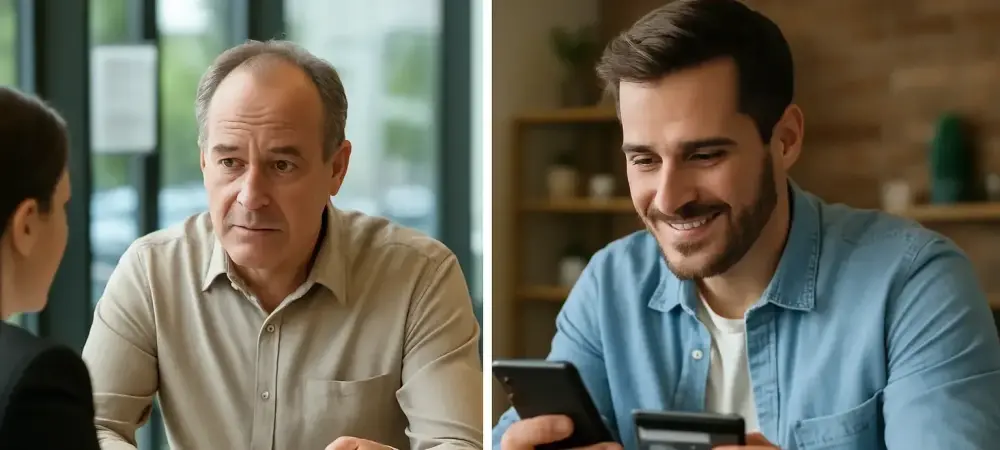
The rapid acceleration of digital commerce has fundamentally reshaped consumer expectations, creating an environment where speed and convenience are no longer perks but baseline requirements for every transaction. In this landscape, the once-unquestioned methods of securing financing are facing a profound challenge from a more agile and integrated competitor, forcing a critical re-evaluation of how businesses and consumers access capital. This evolution pits the established, methodical approach of traditional lending against the seamless, contextual power of embedded lending.
Understanding the Evolution of Lending
For decades, traditional lending has been the bedrock of finance, a system defined by brick-and-mortar banks and specialized financial institutions. This model operates as a distinct, separate process where a borrower must actively step away from their primary activity—such as purchasing equipment—to apply for a loan. It is a deliberate, often paper-intensive journey involving direct interaction with loan officers, manual reviews, and a noticeable time lag between application and approval. This established structure, while reliable, was built for a different era and often struggles to match the pace of modern business. In sharp contrast, embedded lending represents a paradigm shift, weaving financing directly into the fabric of a non-financial customer experience. It is a technology-driven approach where the option to secure a loan appears contextually at the point of need, such as during an online checkout or within a B2B sales platform. This model transforms financing from a separate, cumbersome task into a smooth, integrated feature. Platforms like QuickFi are at the forefront of this transformation, specifically revolutionizing the B2B capital equipment sector by offering a nearly instant, self-service financing solution that directly addresses the speed and efficiency limitations of older models.
Core Models of Lending A Head to Head Comparison
The Customer Journey and Point of Access
The borrower’s experience is perhaps the most striking point of divergence between the two models. The traditional path requires the customer to initiate a separate journey, often involving extensive paperwork, multiple meetings, and a lengthy waiting period for a credit decision. This process is disconnected from the purchase itself, creating friction and potential delays that can jeopardize a sale. It operates on the lender’s schedule, not the customer’s, forcing business to conform to banking hours and procedural delays. Embedded lending completely redefines this journey by integrating financing at the point of sale. The loan offer is presented as a natural part of the transaction, allowing a customer to secure capital without ever leaving the seller’s ecosystem. This is exemplified by QuickFi’s self-service experience, which is available 24/7. A business owner can apply for and receive approval for equipment financing in minutes, using a mobile device, right when they are making the purchase decision. This immediacy removes friction, enhances the customer experience, and dramatically increases the likelihood of closing a sale.
Operational Framework and Technological Infrastructure
Behind the scenes, the operational differences are just as significant. Traditional lending relies heavily on manual processes and legacy systems that are often siloed, leading to inefficiencies and high overhead. Underwriting, documentation, and servicing are handled by different departments, creating a fragmented workflow that is difficult to scale and slow to adapt. This structure is paper-heavy and requires significant human intervention at every stage, from data entry to final approval. Conversely, embedded lending is built on a foundation of automated, end-to-end digital infrastructure. Solutions like the QuickFi Platform as a Service (PaaS) model manage the entire financing lifecycle within a single, cohesive system. This platform handles everything from borrower onboarding and AI-powered credit underwriting to loan structuring, digital documentation, and robust fraud prevention. It also manages full regulatory compliance with KYC, AML, and BSA requirements across the United States and Canada, along with back-end operations like funding and servicing, all without requiring clients to build their own costly infrastructure.
Speed Scalability and Cost Effectiveness
The business impact of these operational differences is profound. The slow, resource-intensive nature of traditional loan origination translates into higher operational costs and a longer time to market for new financing programs. Each loan requires a significant investment of time and personnel, making it difficult to scale operations efficiently without a proportional increase in headcount and expenses. Embedded finance offers a rapid, scalable, and highly cost-effective alternative. By leveraging AI and automation, platforms can process vast numbers of applications with minimal human oversight, dramatically reducing operational costs. For businesses looking to offer financing, this model accelerates speed to market, allowing them to launch new programs quickly and adapt to changing market conditions. The inherent scalability means that transaction volume can increase exponentially without a corresponding surge in operational overhead, providing a clear competitive advantage.
Navigating the Challenges and Limitations
Despite its long-standing presence, the traditional lending model faces significant hurdles in the digital age. High overhead costs associated with physical branches and manual processes put pressure on margins, while a slow adaptation to digital trends has led to declining customer satisfaction among a user base accustomed to instant, on-demand services. The rigid, one-size-fits-all approach struggles to compete with the personalized and convenient alternatives emerging in the market.
Embedded lending, while powerful, is not without its own set of strategic considerations. The complexity of integrating a financing platform into an existing sales or e-commerce ecosystem can be a significant technical challenge. Moreover, this model creates a dependency on third-party technology partners, making the selection of a reliable and secure platform paramount. For lenders and businesses, ensuring a robust security and compliance framework is critical to managing risk in a digital-first environment where data protection and regulatory adherence are non-negotiable.
The Verdict Choosing the Right Path Forward
The comparative analysis revealed a clear distinction between a legacy system and a forward-looking solution. While traditional lending provided a stable foundation for decades, its operational inefficiencies and disjointed customer experience rendered it ill-suited for the demands of the modern digital economy. Its slow pace, high costs, and lack of integration created friction that is increasingly unacceptable to today’s businesses and consumers. In contrast, embedded lending emerged as the superior model for organizations seeking efficiency, scalability, and an enhanced customer experience. By integrating financing directly at the point of need, it transformed a cumbersome process into a seamless feature. The future of lending points toward a deeper integration of AI for advanced functions like agentic fraud detection and fully automated operational processes. This continued evolution signals an undeniable and accelerating shift toward more intelligent, autonomous, and customer-centric financial services.