The quiet transformation of the European financial district reached a definitive crescendo on September 18, 2026, as Riverty Bank S.A. officially shed its identity as a mere payment processor to embrace the full authority of a licensed banking institution. This
The quiet transformation of the European financial district reached a definitive crescendo on September 18, 2026, as Riverty Bank S.A. officially shed its identity as a mere payment processor to embrace the full authority of a licensed banking institution. This
The quiet transformation of the European financial district reached a definitive crescendo on September 18, 2026, as Riverty Bank S.A. officially shed its identity as a mere payment processor to embrace the full authority of a licensed banking institution. This
Deeper Sections Await
The traditional image of a parent handing over a crumpled twenty-dollar bill for lunch money or weekend movies has been replaced by a sophisticated digital interface that prioritizes oversight over universal utility. On August 6, 2026, Google introduced a significant
The rapid retreat of federal oversight in the financial technology sector has fundamentally transformed the relationship between digital lenders and the consumers who rely on their innovative platforms for daily transactions. As the Consumer Financial Protection Bureau shifts its focus
Browse Different Divisions
The traditional image of a parent handing over a crumpled twenty-dollar bill for lunch money or weekend movies has been replaced by a sophisticated digital interface that prioritizes oversight over universal utility. On August 6, 2026, Google introduced a significant
Wall Street analysts are currently projecting a loss of six cents per share for Klarna on a revenue target of nine hundred and ninety-five million dollars for the second quarter. This financial forecast comes at a time when the fintech
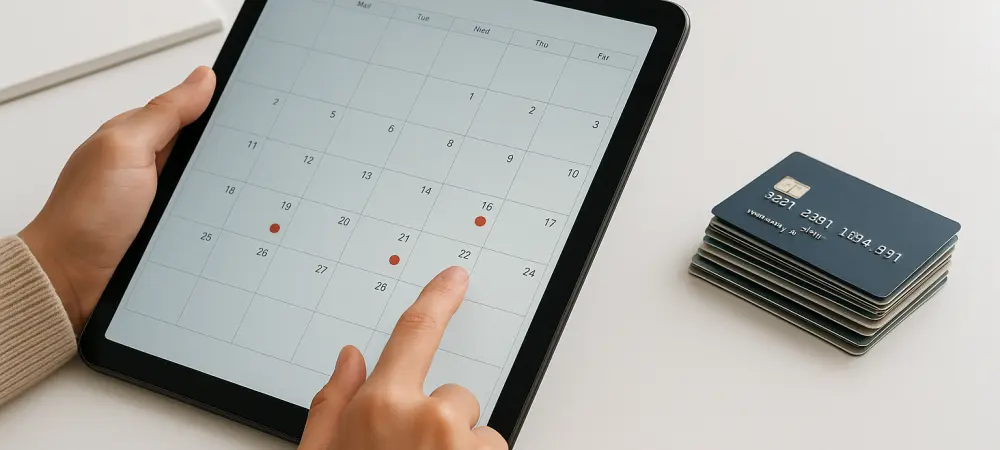
A series of seemingly minor $15 or $20 automated installments can quickly aggregate into a cumulative debt load that exceeds a borrower’s weekly income and compromises household liquidity. This phenomenon marks a departure from traditional lending, where the friction of
Data from LendingTree suggests that 68% of users admit installment services led them to overspend, highlighting the disconnect between perceived affordability and actual cost. This phenomenon has evolved rapidly as Buy Now, Pay Later (BNPL) services have transitioned from niche
Modern entrepreneurs are no longer willing to toggle between dozens of browser tabs just to ensure their morning sales can cover the afternoon’s utility bills or supplier invoices. This friction-heavy reality has historically hampered growth, but the rise of embedded
The rapid retreat of federal oversight in the financial technology sector has fundamentally transformed the relationship between digital lenders and the consumers who rely on their innovative platforms for daily transactions. As the Consumer Financial Protection Bureau shifts its focus
Browse Different Divisions
Uncover What’s Next
B2BDaily uses cookies to personalize your experience on our website. By continuing to use this site, you agree to our Cookie Policy