

Stalled claims, unclear pricing, and clumsy forms once felt like the price of protection, yet daily life now runs on AI shortcuts that set a faster standard for every service interaction, including insurance decisions that used to take days or weeks. That shift showed up in Insurity’s new consumer survey: 84% of U.S. adults use AI at least occasionally and 27% use it daily, reframing algorithms from novelty to utility. This new baseline matters because it recalibrates expectations rather than replacing them. Support for insurers using AI nearly doubled, with 39% calling it a good idea compared with 20% last year, while the share less likely to buy from an insurer that publicly uses AI slid from 44% to 36%. Consumers, however, still draw a practical line between help and authority. Assistive roles earn permission; autonomous judgment remains suspect unless there is meaningful human oversight and clear explanation.
The Shift: Familiarity With AI Meets Insurance Reality
The data points to a public that rewards clarity and speed but resists black-box rulings that touch coverage or money. Comfort rises for everyday, low‑risk tasks: 46% would let AI generate a quote, 39% are fine with AI tracking claim status, and 38% would use it to update personal information. These are chores where AI’s pattern-finding feels like service, not judgment. That ceiling drops when stakes increase. Only 22% would accept AI filing a claim on their behalf, and just 16% are comfortable with an AI canceling or renewing a policy. Moreover, only about one‑third trust AI-led decisions in claims approvals, fraud detection, or policy adjustments, while 26% ask for more information before deciding. That hesitation reflects lessons learned in other sectors where predictive systems deliver speed but can miss context, signaling the need for auditable guardrails.
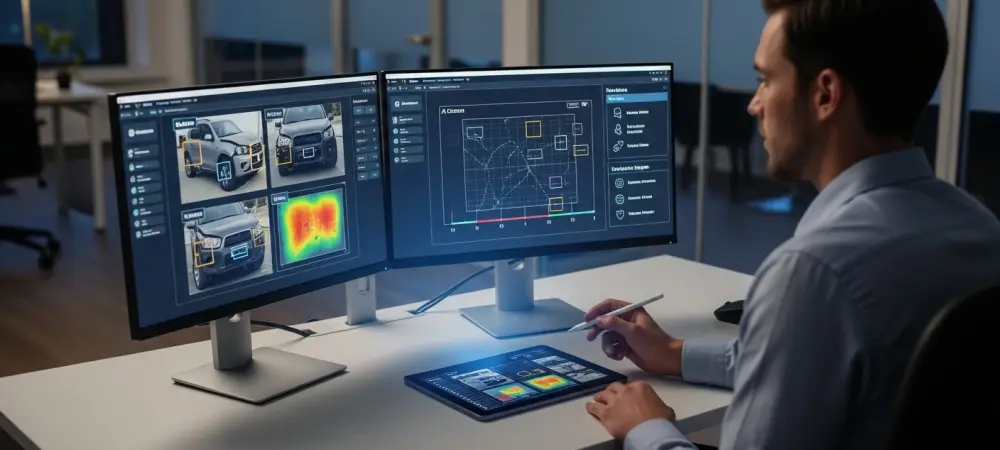
Building on this foundation, insurers are treating AI less as a glossy feature and more as backstage infrastructure. The model in practice looks pragmatic: use large language models to summarize first notice of loss calls, deploy computer vision to pre‑score auto damage photos, and apply anomaly detection to flag suspicious patterns before a human investigator reviews them. In underwriting, gradient boosting or transformer‑based rating models can enrich risk signals, but final pricing still flows through filed rules and compliance checks overseen by licensed professionals. That workflow matches consumer sentiment: let AI draft, rank, and predict; let humans verify, explain, and decide. As Insurity’s leadership argued, AI belongs in the operational stack—monitored, versioned, and measured—rather than in splashy marketing claims that invite skepticism without adding value.
The Line: Human Oversight as the Trust Engine
Consumers appear to accept automation where outcomes are reversible, transparent, and easy to contest, which maps cleanly to quote generation, status tracking, and data updates. Where outcomes affect cash flow or coverage, they want someone accountable in the loop: a named adjuster, an underwriter with authority, a supervisor who can explain the basis of a decision in plain English. This is not technophobia; it is transactional common sense shaped by experience with disputed medical bills or credit scoring quirks. When asked to surrender control at inflection points—approvals, renewals, cancellations—support wanes, indicating that explainability and recourse are not optional features. Even fraud detection, often presented as a pure good, triggers concern if false positives are hard to challenge or if signals cannot be shown without exposing proprietary models.
Translating that preference into operations requires concrete design choices. For claims, straight‑through processing can handle low‑severity, low‑dispute events—think windshield chips or parcel losses—while anything that trips a fairness, materiality, or ambiguity threshold routes to a human. For underwriting, AI‑assisted prefill and risk scoring can speed submissions, but final binds should include a documented rationale referencing filed factors, not opaque vectors. On the customer experience side, chatbots should disclose when a human is available, show source citations for policy guidance, and provide a one‑click path to escalate with full conversation context. Crucially, publish an AI use statement that lists where AI is used, how outcomes are reviewed, and what appeal rights exist. That transparency positions AI as a helpful copilot, not a silent judge.
The Path Forward: Turning Caution Into Confidence
The survey added urgency to governance that many insurers had already begun implementing. A practical roadmap emerged: set thresholds for human review, embed explainability toolkits, and maintain an audit trail that logs features, versions, and overrides. More specifically, carriers should define “decision classes” with clear criteria—such as claim complexity, dollar exposure, or regulatory sensitivity—that determine whether AI recommends or decides. Pair this with performance scorecards that track approval times, overturn rates, and fairness metrics across protected classes. On the customer side, align disclosures with outcomes: if AI proposes a lower premium due to telematics, show the safe‑driving patterns; if it recommends a roof inspection based on aerial imagery, present the annotated tiles. Visible reasoning restores agency.
From a growth perspective, these steps were more than risk control—they were a market signal. With 39% now endorsing AI use by insurers and opposition falling to 36%, the competitive edge shifted toward carriers that converted acceptance into preference through trustworthy design. Executives should prioritize three actions next: pilot AI where consumer comfort is already high and publish results; re‑engineer the claims workflow so adjusters review model rationales rather than duplicate data entry; and invest in customer‑facing explanations that turn denials or adjustments into teachable, respectful interactions. Done well, this approach built resilience, cut cycle times, and raised satisfaction without asking customers to trade fairness for speed. The message had been clear: keep humans visible, make reasoning legible, and earn trust decision by decision.