

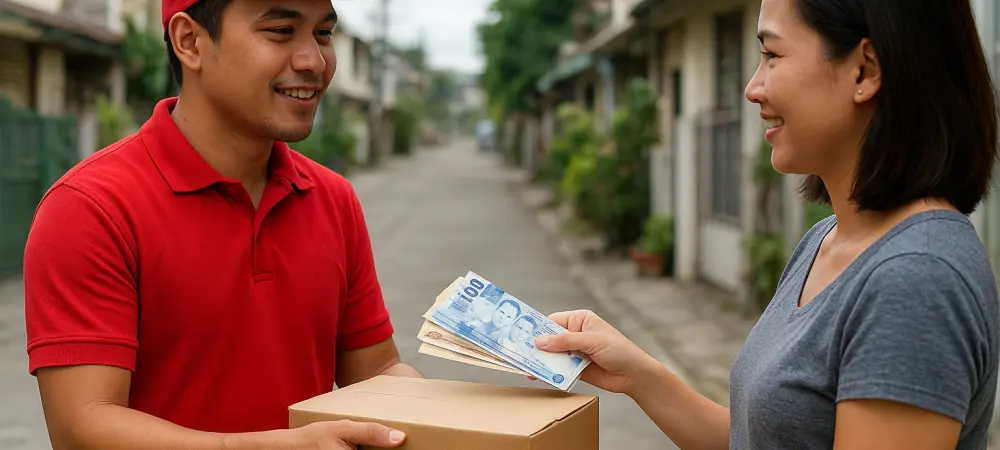
For thirty-three percent of Filipino consumers, the shift away from cash is driven primarily by temporary promotional discounts rather than a permanent change in payment behavior. This reality highlights a unique paradox within the Philippine e-commerce market, where a rapidly growing digital landscape continues to coexist with a deep-seated reliance on physical currency. While the broader Southeast Asian region is pivoting toward digital-first settlement methods, the Philippines remains anchored to cash-on-delivery (COD), which is projected to maintain a share of over twenty percent in online transactions through 2027. This trajectory distinguishes the country as the most cash-reliant shopping market in the region, standing in stark contrast to neighbors where COD is expected to drop below a quarter of total transaction value. Currently, cash represents approximately twenty-three percent of transaction value on major payment platforms, a figure that remains significantly higher than the metrics found in other Southeast Asian markets surveyed.
The Resilience of Physical Currency
Drivers Behind the Continued Use of Cash
The resilience of cash in the local digital economy is primarily fueled by systemic financial gaps that characterize the archipelago’s banking landscape. A substantial portion of the population remains unbanked, lacking access to traditional savings accounts or formal credit facilities that are essential for participating in a cashless ecosystem. For these consumers, physical currency is not just a preference but the only viable medium for exchange, making COD the primary gateway to the digital marketplace. This financial exclusion creates a significant ceiling for digital adoption, as many individuals are structurally prevented from using digital wallets or credit cards. Furthermore, the limited reach of established financial institutions in rural provinces ensures that cash remains the dominant tool for trade, as the infrastructure for digital verification often lags behind the expansion of logistics networks that carry goods to these remote areas, reinforcing a cycle of cash dependency that is difficult to break. Beyond structural barriers, psychological factors such as deep-seated consumer distrust and a fear of delivery fraud play a critical role in maintaining the status quo. Many Filipino shoppers choose to withhold payment until a physical product is in their hands, viewing COD as a vital safeguard against potential scams or subpar merchandise. This skepticism is particularly prevalent among a ‘hardline’ segment of the population, which accounts for twelve percent of shoppers who state that no incentive would convince them to switch to digital methods. This demographic is twice as large as similar groups in neighboring countries, suggesting a cultural resistance that requires more than just convenience to overcome. Until there is a widespread perception that digital platforms can guarantee product quality and security, this psychological barrier will persist. Building trust remains a complex challenge that involves improving not only the technology itself but also the transparency of the entire supply chain.
Impact on Logistics and International Trade
The heavy reliance on cash-on-delivery serves as a significant barrier for international merchants, effectively isolating the Philippine market from many global retail trends. Foreign sellers are often unwilling to accept the inherent risks associated with COD, such as high return rates and the logistical costs of failed deliveries. If a customer refuses a package upon arrival, the international merchant must absorb the expense of shipping, customs duties, and potential stock loss, making the market unattractive for many global brands. Consequently, cross-border shopping in the Philippines remains much lower than in regional peers like Singapore or Thailand. Until digital adoption increases or alternative escrow protections are developed, local consumers will continue to have limited access to the global digital economy, remaining largely confined to domestic storefronts that can accommodate physical currency settlements and local return logistics.
On a domestic level, the prevalence of cash transactions imposes a heavy “tax” on logistics and retail infrastructure through settlement delays and increased operational risks. Couriers must manage the physical security of collected funds, which increases insurance costs and necessitates complex reconciliation processes to prevent internal shrinkage. Retailers often face settlement cycles of up to seven days as cash moves from the courier’s pouch to the bank and finally to the merchant’s account, creating significant cash flow challenges for small businesses. While some platforms have introduced measures like one-time password verification at the point of delivery and requirements for partial advance deposits, reducing the cash-on-delivery ratio remains a long-term hurdle. Industry leaders believe that bringing this figure below the twenty percent threshold will require several more years of aggressive infrastructure development and sustained consumer education.
Emerging Digital Alternatives and Market Shifts
The Rise of National Payment Infrastructures
As the reliance on physical currency begins to wane, the resulting gap is being filled by account-to-account (A2A) payments rather than traditional standalone digital wallets. Between 2025 and 2026, the volume of transactions settled via direct bank transfers and national QR systems surged by a staggering one hundred and ninety-eight percent. This growth is largely attributed to the implementation of national infrastructures like QR Ph and InstaPay, which have provided a unified framework for digital transactions. These systems allow for the instant clearing of funds, offering a level of speed and security that was previously unavailable to the average consumer. By linking directly to existing bank accounts, A2A payments bypass unnecessary intermediary steps, making them an attractive alternative for a growing segment of the middle class. The success of these national initiatives suggests that the next phase of the digital economy will be defined by more integrated banking solutions rather than fragmented apps.
The success of the QR Ph initiative, which now accounts for thirteen percent of the total e-commerce value on major networks, stems from its unprecedented level of interoperability. Unlike early digital payment experiments that required merchants to maintain multiple accounts for different providers, QR Ph allows a single code to accept payments from a wide variety of banking applications and digital wallets. This simplification of the merchant experience is a critical driver of adoption, as it removes the technical and financial hurdles associated with maintaining complex point-of-sale systems. Furthermore, the standardization of QR codes reduces the learning curve for consumers, providing a familiar and reliable interface for transactions at both major retailers and small-scale sellers. As these national systems continue to mature, they are effectively creating a unified digital highway that connects the fragmented parts of the Philippine financial landscape into a single, cohesive ecosystem.
Market Saturation and Future Banking Trends
While A2A payments are seeing explosive growth, the once-dominant digital wallet sector has entered a period of relative stagnation, with growth rates slowing to a modest three percent. This deceleration indicates that the e-wallet market in the Philippines has likely reached a point of saturation, where most consumers who are inclined to use these standalone applications have already done so. The initial novelty of digital wallets, which focused on providing basic payment services to the unbanked, is now being replaced by a demand for more integrated financial services. Consumers are increasingly looking for platforms that offer more than just a place to store money; they want sophisticated tools for savings, investment, and credit management. This shift suggests that the era of the simple payment app is coming to an end, as the market moves toward a ‘super-app’ model where payments are just one feature within a broader suite of comprehensive digital banking solutions. The future momentum of the Philippine digital economy is expected to reside in instant clearing schemes and integrated banking solutions that offer a direct link to a user’s primary financial institution. This transition reflects a maturing market where consumers are becoming more discerning about where they store their capital and how they manage their transaction data. Rather than maintaining balances across multiple disparate digital wallets, shoppers are moving back toward unified accounts that provide a holistic view of their financial health. Financial institutions are responding to this trend by enhancing their mobile applications to compete with fintech startups, offering seamless integration with e-commerce platforms. This convergence between traditional banking and modern fintech is creating a more stable and regulated environment, which may eventually provide the security framework necessary to finally convince the most hesitant cash users to transition into the digital age.
Strategic Evolution of the Digital Economy
The evolution of the Philippine payment landscape required a strategic focus on bridging the gap between physical currency and digital infrastructure. While the rise of national payment systems like QR Ph provided a technical foundation, stakeholders found that long-term success depended on fostering a culture of trust through enhanced consumer protections. Actionable next steps for the industry included the implementation of more robust escrow services and the simplification of the digital refund process to match the immediacy of cash-based refusals. Merchants who adopted these protocols observed a significant reduction in delivery failures and an increase in cross-border trade potential. Future considerations will likely involve the integration of blockchain-based verification to further mitigate fraud and the expansion of digital credit facilities for the unbanked. By addressing the root causes of cash dependency, the market prepared for a future where seamless digital commerce became the standard for all citizens.