

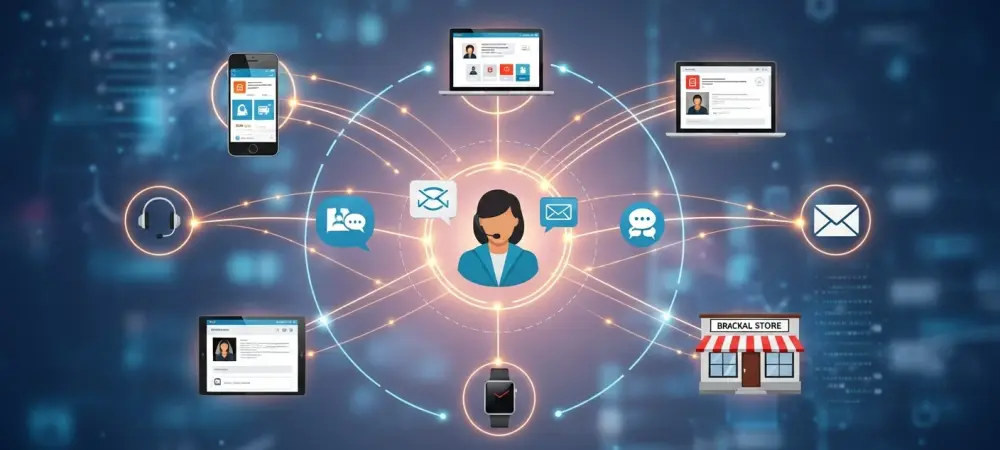
The insurance industry has poured billions into digital transformation, yet the needle on customer satisfaction has barely moved, exposing a deep-seated chasm between technological investment and genuine customer value. This paradox highlights a critical misunderstanding at the heart of many modernization efforts: the difference between simply being present on multiple channels and delivering a truly integrated, seamless omnichannel experience. While a multichannel approach offers various disconnected touchpoints, a genuine omnichannel strategy weaves them together into a single, continuous customer journey, representing the ultimate competitive differentiator in a crowded market.
This analysis will delve into the current state of customer communication, revealing why significant digital spending has not yielded proportional gains in satisfaction. It will explore the crucial link between interaction consistency and customer trust, the non-negotiable demand for choice and personalization, and the significant business cost of interaction friction. Ultimately, this examination will map the future trajectory of the insurance industry, moving toward a model defined by holistic journey orchestration and genuine customer empowerment.
The Current State of Omnichannel Adoption
The Digital Paradox: Investment vs. Impact
A persistent and troubling trend has emerged in the insurance sector’s quest for digital maturity. Despite substantial investments in mobile applications, online portals, and AI-powered tools, the impact on customer sentiment has been underwhelming. Data from a 2026 Smart Communications report reveals that customer satisfaction with omnichannel experiences has stagnated at 54%, showing no improvement from the previous year. This plateau suggests that simply adding more digital channels does not automatically create a better experience. The root of this issue lies in a common strategic misstep: insurers are frequently digitizing outdated, linear processes rather than fundamentally re-engineering them for a digital-first environment. Bolting a new app onto a decades-old workflow or creating a web portal that doesn’t sync with the call center’s systems only multiplies the potential points of frustration. Instead of streamlining the customer journey, this approach often complicates it, creating a digital facade that masks an inefficient and fragmented core.
Real-World Scenarios of a Disconnected Journey
The consequences of a fragmented strategy are not abstract; they manifest in common, frustrating experiences for policyholders. A prime example is a customer who initiates a claim through a mobile app, providing photos and details, only to call the support center and be asked to repeat the entire story from the beginning. This disconnect immediately negates the convenience the app was designed to provide.
These failures erode the customer experience and actively undermine the digital investments made by the insurer. When an online portal fails to reflect a recent payment made over the phone, or a renewal notice arrives by mail days after the policy was updated online, the customer feels unheard and undervalued. Each instance of poor synchronization reinforces the perception that the insurer’s channels operate in silos, creating a disjointed journey that breeds distrust and dissatisfaction.
Core Drivers of Omnichannel Success
Building a Foundation on Trust and Consistency
Trust has always been the bedrock of the insurance relationship, but its definition has expanded in the digital age. Today, trust is built not only on brand reputation and financial stability but on the reliability and seamlessness of every single interaction. Expert analysis, supported by compelling data, confirms this shift: 60% of U.S. consumers report that they place more trust in companies that provide consistent interactions across all channels.
This finding elevates consistency from a desirable feature to a critical business imperative. In a true omnichannel environment, a conversation that begins via chatbot can be seamlessly escalated to a human agent who has the full context of the interaction. This continuity demonstrates respect for the customer’s time and intelligence. Conversely, when touchpoints are not synchronized, trust is fractured, transforming what should be a straightforward process into an ordeal and damaging the customer relationship at its core.
The Mandate for Customer Choice and Personalization
Modern customers expect to engage with businesses on their own terms, using the channels that are most convenient for them at any given moment. However, industry data reveals a growing gap between customer expectations and insurer practices. Only 55% of U.S. insurance customers feel their provider uses their preferred communication channel, a noticeable drop from 60% the previous year. This decline signals that insurers are failing to keep pace with evolving preferences.
The communication landscape is incredibly fragmented; there is no single dominant channel. To succeed, insurers must offer a flexible and secure menu of options—including email, SMS, web portals, and encrypted messaging—and empower customers to select their preferred method. The expert consensus is clear: the era of one-size-fits-all communication is over. Respecting customer choice is no longer optional but a fundamental requirement for building and maintaining loyalty in a consumer-driven market.
Quantifying the High Cost of Interaction Friction
In an environment of on-demand services, customer tolerance for complexity has plummeted. Every unnecessary step, confusing interface, or disconnected channel creates friction, which carries a direct and significant business cost. A key insight reveals that 65% of policyholders are likely to abandon a process they perceive as too complicated. This figure climbs to over 70% for Millennials and Gen Z, who constitute the industry’s next wave of core customers.
This high abandonment rate translates directly into lost revenue, from incomplete quote applications to policy non-renewals and missed cross-selling opportunities. From an industry perspective, friction is a direct barrier to growth. The strategic response must be a relentless focus on simplification, using smarter digital tools like pre-filled forms, intuitive guided workflows, and context-aware communications to create an effortless experience. Reducing friction is no longer just about improving satisfaction; it is a core strategy for customer retention and profitability.
The Future Trajectory of Customer Experience
The Evolution from Channel Management to Journey Orchestration
The forward-thinking trend in customer experience is a move away from simply managing a portfolio of separate channels toward orchestrating holistic, end-to-end customer journeys. This evolution requires a fundamental shift in thinking, where the focus is not on the performance of an individual channel but on the seamless flow of the customer through their entire lifecycle with the insurer, from initial quote to claim resolution.
In this future state, interactions will become more intuitive and proactive. Widespread adoption of pre-filled forms will eliminate redundant data entry, while guided digital workflows will steer customers through complex processes with ease. Furthermore, context-aware communications will ensure that every message is relevant and timely, picking up precisely where the last interaction left off. This level of orchestration creates a truly effortless and continuous journey that anticipates customer needs before they are even expressed.
The Competitive Imperative of Customer Empowerment
Ultimately, the primary differentiator in the insurance market will be the degree to which customers are empowered to control their own experiences. This means giving policyholders genuine authority to dictate when, where, and how they engage with their insurer. Such a model requires a profound change in the industry’s mindset, moving away from traditional, one-way communication to customers and embracing a collaborative partnership with them.
The challenge lies in building the technological and cultural infrastructure to support this collaborative model. It demands integrated systems, transparent processes, and a commitment to listening and responding to customer preferences in real time. Insurers that successfully make this transition will not only meet modern expectations but will also forge deeper, more resilient relationships with their policyholders, solidifying their competitive advantage for years to come.
Conclusion: The Path to a True Omnichannel Future
The analysis revealed the stark inadequacy of a simple multichannel presence in meeting modern customer expectations. The findings underscored that the path to success was paved not with more technology, but with more thoughtfully integrated technology. The critical roles of trust built through consistency and loyalty earned through customer choice became undeniable business imperatives. Furthermore, the direct correlation between interaction friction and lost revenue established a clear financial case for investing in seamless, orchestrated customer journeys.
This examination concluded that a fundamental mindset shift was necessary for insurers to thrive. The journey from a channel-centric model to a customer-centric one required more than just new tools; it demanded a new philosophy. The insurers poised to lead the market were those that committed to putting customers in the driver’s seat, transforming every touchpoint into an opportunity to build trust, demonstrate value, and earn a sustainable competitive advantage.