

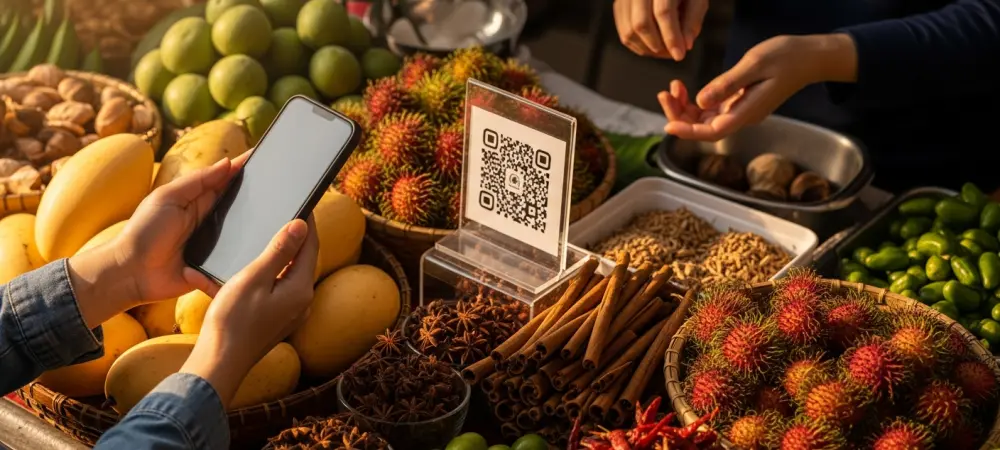
A single square of black and white pixels has managed to replace the clunky machinery of traditional banking across the vibrant markets of Jakarta and the bustling streets of Bangkok. This digital revolution has not only streamlined how millions of people buy their daily necessities but has also fundamentally altered the financial landscape of the entire region. Unlike the slow adoption of credit cards in the past, QR code technology provides a low-entry barrier for both street vendors and large retailers, creating an ecosystem where cash is no longer the undisputed king. The sheer speed of this transition highlights a significant shift in consumer behavior, as mobile-first populations embrace the convenience of scanning to pay over the tactile exchange of physical currency. With regional central banks now working in tandem to link these local systems, the fragmentation that once defined Southeast Asian trade is rapidly dissolving into a unified digital marketplace. As the technology matures, it fosters a more inclusive economy for the unbanked population.
The Infrastructure of Regional Payment Connectivity
The Role of Cross-Border Integration and Standardized Protocols
Central banks across the Association of Southeast Asian Nations have orchestrated a sophisticated network of payment linkages that allow travelers to use their home country’s e-wallets in neighboring territories. For instance, a Malaysian tourist visiting Singapore can now use the DuitNow app to scan a PayNow QR code, with the currency conversion occurring instantly at competitive mid-market rates. By eliminating the need for physical currency exchange or expensive international credit card fees, these linkages have stimulated regional tourism and micro-trade. The technical groundwork involves complex API integrations between national switches, ensuring that a transaction initiated in one country is recognized and cleared in another within seconds. This infrastructure serves as a blueprint for other emerging markets seeking to reduce reliance on global payment giants.
Economic Empowerment through Micro-Merchant Accessibility
For small and medium-sized enterprises, the barriers to accepting digital payments have historically been prohibitively high due to the costs of hardware and transaction fees. However, the introduction of static QR codes printed on simple paper placards has allowed even the smallest street-side vendors to accept digital transfers without any upfront investment. This democratization of financial tools has been particularly impactful in rural areas where traditional banking infrastructure is sparse. In markets like Vietnam and the Philippines, the surge in QR adoption has provided merchants with a digital footprint, which they can later use to secure credit or insurance services that were previously out of reach. By bypassing the need for expensive point-of-sale terminals, the QR model has effectively lowered the cost of entry for digital commerce. This shift not only increases the safety of transactions by reducing the risks associated with carrying cash but also helps businesses manage their cash flows with greater precision.
Consumer Trust and the Security Framework
Advanced Safeguards and Real-Time Fraud Mitigation
As the volume of digital transactions increases, the focus has shifted toward securing the ecosystem against sophisticated cyber threats and fraudulent activities. Modern QR payment systems utilize dynamic codes that change for every transaction, incorporating unique tokens that expire after a set duration. This approach prevents replay attacks where a malicious actor might attempt to reuse a static code to divert funds. Furthermore, the integration of biometric authentication, such as fingerprint or facial recognition on mobile devices, adds a robust layer of security that traditional PINs cannot match. Regional regulators have also played a crucial role by establishing clear guidelines on liability and consumer protection, which has been instrumental in building public trust. Encryption standards have been upgraded to protect sensitive data during transit, ensuring that personal information remains confidential even in the event of a network breach. These advancements are vital for maintaining the integrity of the payment network.
Strategic Evolution of the Financial Super App Ecosystem
The rise of QR payments has been inextricably linked to the dominance of regional super apps, which offer a wide range of services from ride-hailing to food delivery within a single interface. These platforms have successfully leveraged their massive user bases to drive the adoption of their proprietary digital wallets, which are now being integrated with national QR standards. This integration allows users to pay for services across different merchants without ever leaving their preferred app environment. Stakeholders focused on the long-term viability of these digital systems by prioritizing the standardization of protocols across different borders. Regulators moved away from restrictive policies and instead fostered innovation through regulatory sandboxes, which allowed for the safe testing of new financial technologies. Businesses integrated their payment systems with broader data analytics tools to gain deeper insights into consumer behavior. These steps ensured that the infrastructure remained robust and adaptable to the needs of the global economy.