

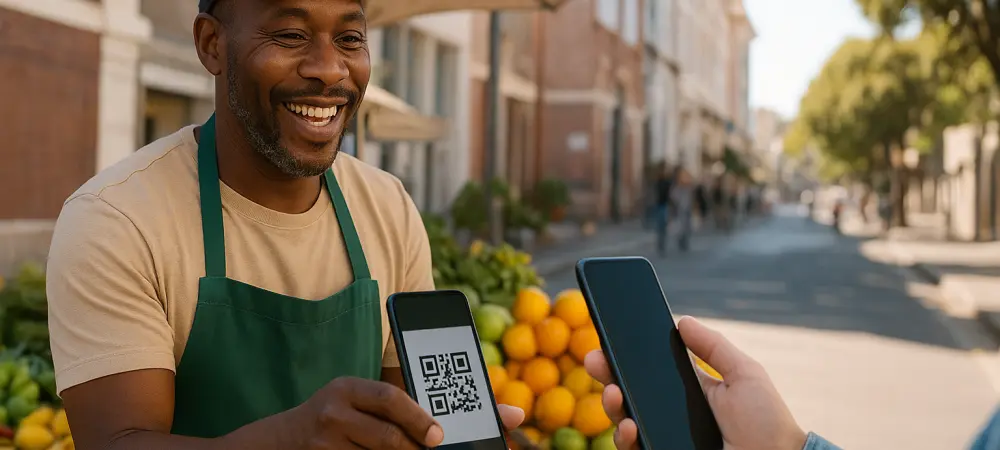
By allowing non-banks to initiate payments and remit money directly, the South African government expects to foster a more inclusive and innovative digital landscape. This monumental shift marks the end of an era where traditional banking institutions served as the sole gatekeepers of the national payment infrastructure, often creating bottlenecks for smaller financial technology players. For decades, the South African Reserve Bank (SARB) maintained a hierarchy that required telecommunications companies and retail giants to partner with established banks to clear and settle transactions. This dependency frequently resulted in higher fees for consumers and a slower pace of innovation, as agile startups were forced to navigate the legacy systems of their larger competitors. As the country moves through 2026, the central bank is finalizing a legislative framework designed to dismantle these barriers, ensuring the payment ecosystem reflects a modern digital reality.
Bridging the Divide: Financial Accessibility in 2026
Part 1. Dismantling the Traditional Banking Monopoly
The primary catalyst for this systemic change is the Payments Ecosystem Modernisation program, a strategic initiative spearheaded by the South African Reserve Bank to revitalize the country’s financial architecture. Pradeep Maharaj, a prominent official at the central bank, recently emphasized that while the existing infrastructure established by banks is technically sound, its governance has been plagued by inconsistent application of rules. This inconsistency has led to a fragmented experience for users, where transaction limits and processing times vary wildly depending on which intermediary is involved in the process. By removing the mandatory bank intermediary requirement, the government aims to level the playing field for fintech startups and retail chains. This reform is not merely about technical access; it represents a fundamental reordering of economic power, shifting control from legacy institutions to a broader spectrum of service providers better positioned to serve the locals.
Part 2. Establishing a Streamlined Regulatory Framework
The overhaul specifically targets seven key payment activities that were previously the exclusive domain of licensed banks, including the issuance of e-money and the direct acquisition of merchants. By granting non-bank entities the authority to handle payment initiation and money remittances, the SARB is creating a streamlined regulatory environment that encourages competition based on service quality rather than institutional status. This shift is particularly significant for the millions of South Africans who rely on informal trade, as these businesses can now bypass the complex fee structures typically associated with traditional commercial banking. The transition is governed by a strict regulatory timeline that began with the release of the National Payment System Bill in September 2026. This legislative foundation will be followed by finalized rules in November 2026, setting the stage for a new generation of financial service providers to scale without any unnecessary costs.
Infrastructure and Technological Integration: The Path Forward
Part 3. Scaling Digital Services and Payment Standards
To ensure that the expanded payment ecosystem remains cohesive, the South African Reserve Bank is prioritizing the rapid scaling of PayShap, a fast-payment service that has already gained significant traction. Currently processing approximately 60 million transactions every month, the goal is to increase this volume to 500 million monthly transactions by 2029 through broader adoption by non-bank participants. Accompanying this push is the introduction of a standardized QR+ payment code system, which is scheduled for deployment in late 2026. This technology will allow even the smallest street-side merchants to accept digital payments without the traditional merchant fees that have historically made card payments unviable for low-margin businesses. By integrating these standardized tools, the SARB is building a digital highway that allows money to flow seamlessly between different platforms, whether a consumer is using a mobile wallet from a provider or a specialized app.
Part 4. Strategic Actions for a Resilient Financial Core
The implementation of these reforms provided a clear roadmap for other emerging markets seeking to balance financial stability with rapid technological evolution. Stakeholders recognized that the success of this transition depended on the rigorous enforcement of security standards and the proactive engagement of non-bank entities with the new regulatory framework. Moving forward, businesses should have prioritized the integration of the standardized QR+ system to capture the growing segment of digital-first consumers. Policymakers also highlighted the need for continuous monitoring of transaction fees to ensure that the promised cost reductions actually reached the end-user. By fostering a collaborative environment between traditional banks and new fintech entrants, South Africa established a more resilient financial core that reduced systemic reliance on cash and improved economic transparency. These actions eventually paved the way for more sophisticated financial products for the nation.