

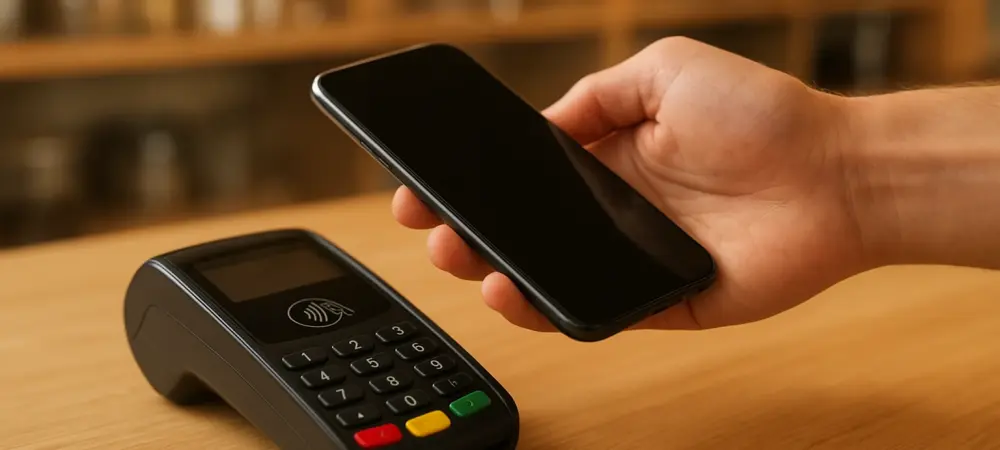
Standing in a crowded supermarket queue during the evening rush often highlights the minor frustrations of digital payments when every second counts for weary commuters. The rapid evolution of mobile financial services has reached a significant milestone with the commercial debut of a new contactless interface designed to accelerate these moments of daily commerce. The new system allows for a frictionless experience where the user simply brings their device close to a payment chip to initiate a secure data transfer without any manual input. This shift represents a departure from the traditional USSD-based interaction model that has dominated the region for years. By implementing Near Field Communication technology, Safaricom is addressing the growing demand for speed and efficiency at high-traffic retail points. The integration is expected to reduce the average transaction time by nearly sixty percent, effectively eliminating the bottleneck of manual PIN entry for small-value purchases. As the digital economy expands, this innovation ensures that mobile money remains a highly reliable alternative to cash in a fast-paced environment.
1. Technical Infrastructure: Implementing Secure NFC Protocols
Implementation of this tap-to-pay functionality requires a sophisticated backend that synchronizes the M-PESA balance with the hardware-level encryption of modern smartphones. Safaricom has collaborated with global hardware manufacturers to ensure that the security keys used for these contactless interactions are stored within a dedicated secure element on the device. This approach prevents unauthorized access to the user’s financial credentials, even if the primary operating system is compromised. Furthermore, the system is designed to handle varying levels of connectivity, ensuring that a handshake between the handset and the terminal occurs rapidly without significant latency. The integration also includes support for wearable devices, allowing customers to use smartwatches for payments, which significantly broadens accessibility for a tech-savvy demographic. Such technical foresight ensures the infrastructure remains relevant throughout the current cycle ending in 2027.
Beyond the consumer-facing hardware, the merchant ecosystem is receiving a massive upgrade to accommodate the shift toward contactless standards. Small and medium-sized enterprises are being provided with affordable NFC-enabled till numbers and modernized payment terminals that can process these encrypted signals instantaneously. This democratization of high-end financial technology allows a local kiosk owner to offer the same level of service as a large international retailer. The rollout includes comprehensive training programs for business owners to understand the nuances of tap-to-pay, such as transaction limits and verification protocols for higher-value purchases. By reducing the reliance on physical cash and the typing of long till numbers, the error margin for manual entries is virtually eliminated. This change not only boosts operational efficiency but also provides a more sanitary payment method, which has become a significant priority for many urban residents today.
2. Economic Impact: Driving Regional Financial Inclusion
The introduction of this contactless layer is set to trigger a secondary wave of innovation within the local fintech space, as developers build new applications on top of the Tap-to-Pay API. Financial analysts suggest that this movement will likely lead to an increase in the frequency of micro-transactions, as the barrier to completing a payment is lowered to a mere gesture. This behavioral shift is expected to drive higher revenue for service providers and increased tax transparency for the government, as more informal transactions move into the digital ledger. Moreover, the data generated from these interactions provides invaluable insights into consumer spending habits, allowing for more personalized financial products such as tailored credit scores and insurance premiums. As other regional players look toward this model, the standardization of NFC payments across the region could facilitate more seamless cross-border trade. The focus is now shifting toward ensuring that the network remains resilient against fraud.
Looking back at the initial deployment phase, the move to incorporate NFC technology successfully addressed critical bottlenecks that had previously hindered the total digitization of the retail sector. Safaricom transitioned millions of users toward a more modern interface, effectively setting a new benchmark for mobile money services globally. Moving forward, the industry must prioritize the expansion of this hardware compatibility to entry-level devices to ensure that the benefits of contactless payments are not limited to premium smartphone users. Financial institutions should focus on establishing interoperability standards that allow different mobile wallets to communicate with the same merchant terminals, fostering a competitive market. Regulators were instrumental in creating a framework that protected consumer interests while encouraging this rapid pace of innovation. As the ecosystem matured throughout 2026, the emphasis shifted toward integrating loyalty programs and automated tools into the daily tap-to-pay workflow.