

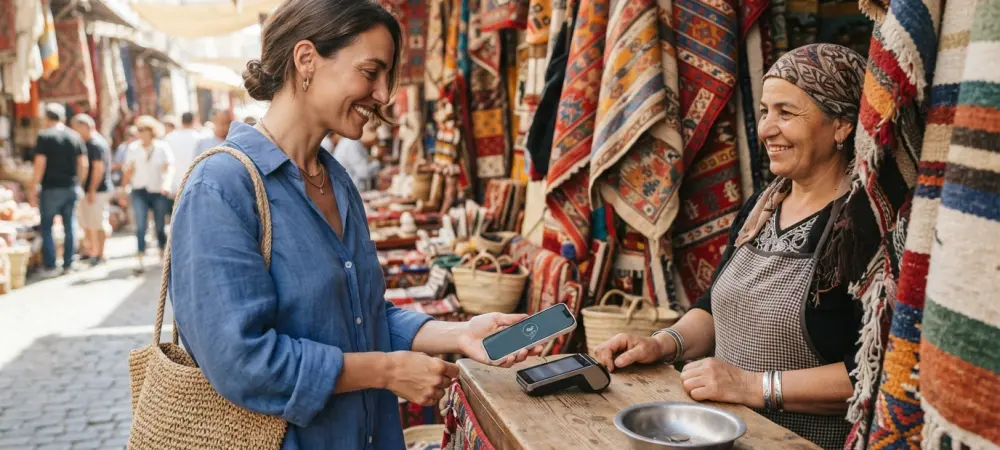
Widespread adoption of tap-to-pay technology depends on the availability of compatible hardware and a significant shift in consumer habits across the Nigerian retail sector. This transition is not merely about replacing physical cards but about addressing the bustling energy of Lagos markets where the slow, multi-step process of mobile bank transfers often creates unnecessary friction. As financial institutions look toward the horizon from 2026 to 2028, the emphasis has shifted from merely digitalizing accounts to optimizing the point of interaction. This transformation is driven by a strategic alliance between Interswitch and major banking players like Wema Bank and GTBank, aiming to replace physical card reliance with secure digital tokens. By integrating Near Field Communication and biometric authentication, the ecosystem is moving toward a reality where a simple gesture completes a transaction, finally matching the speed of modern life in Nigeria’s urban centers.
The Convergence: Secure Technology and Public Infrastructure
At the heart of this technological surge lies tokenization, a sophisticated security protocol that fundamentally alters how sensitive financial data is handled during a transaction. Instead of transmitting actual debit or credit card numbers, which can be intercepted or skimmed, the system generates unique digital identifiers known as tokens. These tokens carry no intrinsic value and are specific to a single device or merchant environment, ensuring that even if data is compromised, the original account remains shielded. Interswitch Purepay has positioned tokenization as the bedrock of its contactless strategy, emphasizing that reducing friction does not have to come at the expense of safety. By removing the need for a physical card or for a user to type in a PIN on a communal terminal, the process minimizes physical touchpoints and potential vectors for fraud, streamlining the checkout experience for the modern consumer while maintaining rigorous standards. Furthermore, the integration of biometric authentication adds a layer of personalization and security that traditional plastic cards cannot match. By utilizing facial recognition or fingerprint scanning stored locally on a mobile device, users can authorize payments in milliseconds without remembering complex passwords. This seamless interaction is designed to replace the cumbersome mobile app-based transfers that have dominated the Nigerian market for years. While those transfers were a necessary stepping stone, they often require five or six distinct steps, including selecting a bank, entering an account number, and confirming the recipient’s name. In contrast, the tap-to-pay model leverages the pre-validated identity of the device owner, effectively condensing the entire payment journey into a single, secure action. This efficiency is expected to increase transaction volumes in high-traffic retail environments where speed is the primary driver of customer satisfaction. The practical application of contactless payments extends far beyond grocery stores, promising to revolutionize public infrastructure and urban mobility across Nigeria’s major cities. Banking leaders at Wema Bank have identified the transportation sector, specifically the BRT bus systems and the expanding Lagos rail network, as the ideal proving ground for this technology. In these environments, the delay caused by cash handling or manual ticketing creates significant bottlenecks that hinder economic productivity. Transitioning to a tap-to-pay model allows commuters to simply tap their phones or smartwatches at turnstiles, mirroring the efficiency seen in global financial hubs. Simultaneously, merchant behavior is gravitating toward these solutions as vendors upgrade their Point of Sale terminals to support NFC technology. This infrastructure shift is crucial because the convenience of tap-to-pay is only realized when it is ubiquitous across the entire retail landscape. The initiative to standardize contactless payments successfully laid the groundwork for a more cohesive digital economy by aligning local infrastructure with global standards. Financial institutions moved to prioritize the onboarding of small and medium-sized enterprises, ensuring that even neighborhood kiosks could access NFC-enabled software solutions. It became clear that the next phase of growth required consistent regulatory support to ensure interoperability between different banking platforms and payment service providers. Stakeholders focused on nationwide education campaigns to demystify tokenization for the unbanked populations, fostering trust in digital-first interactions. This collaborative effort transformed the retail landscape into a more secure environment, where the reliance on physical currency and manual transfers significantly decreased. By 2027 and beyond, the focus shifted toward integrating these systems with cross-border payment corridors to expand the economy.