

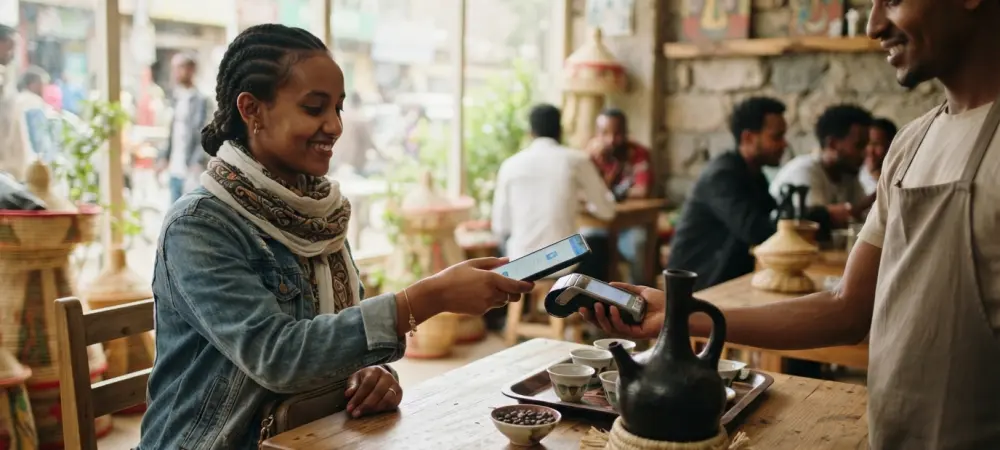
Senior executives at the Sheraton Addis Hotel recently unveiled a payment solution that removes the physical barriers of scanning codes by utilizing location-based merchant identification. This strategic rollout represents a significant leap forward in the domestic digital finance ecosystem, where convenience and speed have become the primary drivers of consumer behavior. By integrating the AirPay feature into the widely utilized Dashen Super App, the financial institution is effectively addressing the common frustrations associated with traditional electronic payments, such as the manual entry of long account strings or the failure of mobile cameras to recognize damaged QR code stickers. The atmosphere at the launch event reflected a broader national trend toward a cashless economy, as stakeholders from across the business community gathered to witness a demonstration of ambient payment technology. This system moves beyond the limitations of hardware-dependent scanning, focusing instead on a seamless software-driven discovery process that connects customers to businesses through proximity.
1. Mechanics of the Location-Based Discovery Feature
Accessing the new functionality requires minimal effort from the consumer side, as the interface is designed to prioritize intuitive navigation over complex administrative steps. Upon opening the banking application and selecting the dedicated AirPay option, the user is presented with a real-time list of registered merchants operating within their immediate geographical vicinity. This elimination of the need for phone numbers or specific bank details reduces the cognitive load on the customer and minimizes the risk of sending funds to the wrong recipient. Once the correct business is identified from the digital list, the user simply enters the desired transaction amount to proceed. This streamlined workflow is particularly beneficial in high-traffic retail environments, such as busy supermarkets or bustling cafes, where the speed of service directly impacts customer satisfaction and turnover rates. By removing the friction of manual data input, the bank has created a more accessible entry point for users who may have previously found digital banking tools to be overly cumbersome for daily micro-transactions.
Security remains a foundational pillar of this account-free system, ensuring that ease of use does not come at the expense of financial integrity. While the merchant discovery process is automated through location services, the actual transfer of funds is protected by a mandatory personal identification number that the user must enter to authorize the movement of capital. This dual-layer approach combines the convenience of proximity-based detection with the rigorous safety standards expected of a Tier 1 commercial bank. Interestingly, the platform supports transactions without a predefined maximum limit, though it remains subject to the prevailing regulatory frameworks and individual account-level restrictions established by the central authority. By enabling payments to be finalized within seconds, the system provides a robust alternative to cash, offering a digital paper trail that is essential for modern accounting and tax compliance. Furthermore, the bank has emphasized that this technology is not merely a payment tool but a bridge that strengthens the digital bond between local consumers and the domestic businesses that serve them, fostering a more connected community.
2. Evaluating Market Dynamics and Digital Growth Trends
The introduction of this service coincides with a period of unprecedented growth in the national payment infrastructure, as evidenced by recent data from the national payments switch operator, EthSwitch. During the 2025/26 financial year, interoperable digital transactions surged to 387 million, representing a total value of approximately 7.8 billion US dollars. While person-to-person transfers dominated this landscape, accounting for roughly 6.6 billion US dollars of the total volume, QR-code based payments remained a relatively untapped segment with only about 551,500 recorded transactions. This disparity suggests that while citizens are comfortable moving money between individuals, the barriers to merchant-specific digital payments remain high. The AirPay solution specifically targets this discrepancy by offering a more user-friendly discovery method that could potentially bypass the physical and technical hurdles that have limited the adoption of QR codes. As the industry continues to expand, the push toward more integrated and proximity-aware financial services is expected to become the new standard for commercial interactions.
To maximize the benefits of this technological shift, local merchants should prioritize the formal registration of their business details and customer information within the new platform to ensure visibility in the discovery feed. Strategic implementation of this service involves not just adopting the software, but also training frontline staff to guide customers through the proximity-based payment process. Moving forward, the industry must address the challenge of cross-platform compatibility to ensure that these location-based features can eventually interact with mobile applications from other financial institutions. The bank succeeded in demonstrating that reducing transaction friction is essential for sustaining the current momentum of digital adoption. By focusing on the removal of physical identifiers and the promotion of ambient connectivity, the financial sector is laying the groundwork for a future where commerce is defined by ease of access rather than technical complexity. Businesses that lean into these location-aware solutions will likely find themselves better positioned to capture the growing segment of tech-savvy consumers who demand efficiency in every transaction.