

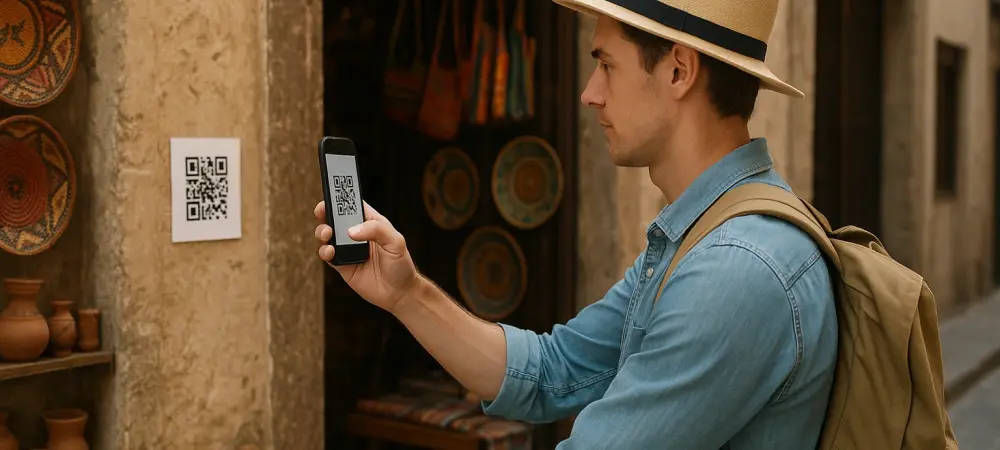
Global commerce is currently undergoing a radical shift where scanning a simple black-and-white square replaces the cumbersome exchange of physical bills or high-fee credit cards. This transition from fragmented domestic wallets to a unified global payment ecosystem signifies a new era of connectivity. QR codes have emerged as the primary vehicle for financial harmony due to their low implementation costs and high utility for both merchants and consumers.
Breaking Down the Barriers to Borderless Digital Commerce
The move toward an integrated landscape allows travelers to use familiar apps in foreign markets. This shift reduces the reliance on physical cash while providing a standardized interface for diverse populations. Real-time settlement and interoperability are now reshaping the travel experience by making transactions as quick as a local purchase.
The Evolution of QR Codes from Domestic Silos to Global Standards
Walled gardens once defined the digital payment space, creating isolated regional schemes that frustrated international users. Emerging markets like Brazil and Singapore led the change by choosing QR infrastructure over traditional card rails. This decision was driven by the economic necessity of connecting local merchants with the growing sector of international tourism.
The Strategic Path Toward Interoperable Global Payments
1. Dismantling the Walled Gardens of Domestic Schemes
Modern frameworks focus on shifting from closed-loop systems to open-access international networks. This strategy ensures that a user from one country can pay a vendor in another without requiring a specific local account.
Real-Time Settlement as the Foundation
Instant transaction processing eliminates the lag inherent in traditional banking systems. By finalizing payments immediately, the system provides liquidity and trust for small-scale merchants who operate on tight margins.
Reducing Friction for the International Traveler
Tourists benefit significantly by bypassing physical currency exchange offices. This method avoids the high fees and unfavorable rates typically associated with traditional credit card transactions abroad.
2. Integrating National Infrastructure with Global Platforms
Fintech leaders like Wise are bridging the gap between local applications and international users. This technical bridge allows for a seamless flow of funds across borders without the need for complex intermediary banks.
Direct App Integration for Seamless UX
Embedding domestic schemes like Pix and PayNow into international wallets creates an intuitive user experience. Users scan a local code, and the backend handles the complex routing required to complete the payment.
Leveraging API Connectivity for Instant Currency Conversion
Transparent exchange rates are guaranteed at the point of sale through real-time data feeds. This ensures that the buyer knows the exact cost in their home currency before confirming the scan.
3. Scaling Reach Through Strategic Aggregator Partnerships
Massive networks like Alipay+ play a vital role in consolidating regional QR standards. These aggregators serve as a single point of entry for various digital wallets across different continents.
Unifying Diverse Asian and Latin American Standards
Partnerships simplify the merchant landscape by removing the need for multiple scanners. A single QR code on the counter can now accept dozens of different international payment apps simultaneously.
Standardizing the QR Interface for Universal Recognition
The movement toward a recognizable code format ensures that travelers recognize where they can pay. Universal standards help build consumer confidence in digital payment points regardless of the destination.
4. Harmonizing Cross-Border Regulatory and Technical Protocols
Collaboration between central banks is linking national payment grids to facilitate smoother trade. These efforts ensure that technical systems are compatible and legally compliant across different jurisdictions.
Bilateral Agreements and the Indonesia-China Case Study
Linking the QRIS system with UnionPay has facilitated massive regional trade and tourism. Such agreements serve as blueprints for other nations looking to boost their economic ties through digital means.
Establishing Global Security and Privacy Benchmarks
Protecting user data is a top priority as systems become more interconnected. Robust protocols maintain the speed and convenience of QR payments while defending against modern digital threats.
Summary of the Integrated Payment Journey
Isolated domestic schemes are rapidly becoming relics as interconnected global networks take over. The integration of local favorites like Pix and QR Ph into fintech platforms has simplified the payment process for millions. Payment aggregators played a vital role in this transformation by unifying the merchant experience. Real-time, low-cost settlement has officially become the new benchmark for global financial interactions.
Future Implications for the Global Financial Landscape
The QR-first approach will continue to challenge the dominance of traditional credit card networks. This shift promotes financial inclusion by allowing even the smallest vendors to participate in the digital economy. While cybersecurity remains a challenge, the trend points toward a world where a single wallet functions everywhere. International fraud prevention will need to evolve alongside these lightning-fast transaction speeds.
Final Verdict: Embracing a Frictionless Financial Future
Interoperability fostered unprecedented economic growth and provided immense consumer convenience. Businesses that adapted to the new era of QR-driven commerce gained a significant advantage in the global market. The harmonization of regional innovations proved to be the key to long-term global prosperity. Travelers enjoyed a world where financial borders no longer hindered their ability to explore and spend.