

With the African fintech landscape buzzing over Flutterwave’s landmark acquisition of open banking provider Mono, we sit down with an industry expert to dissect what this all-stock deal, valued at up to $40 million, truly signifies. This conversation explores the strategic vision behind letting Mono operate independently, the tangible impact of bank-based payments on everyday users, and the roadmap for next-generation financial products like stablecoins. We’ll uncover how this partnership, years in the making, is set to redefine the continent’s payment infrastructure, moving beyond traditional card rails toward a more connected and secure financial future.
The article notes your partnership began in 2021. Could you share an anecdote from that early collaboration that signaled this acquisition was the right move, and how does the all-stock deal structure, valued up to $40 million, reflect that long-term strategic alignment?
I remember when we first started collaborating on bank payment products back in 2021. There was a palpable energy. We saw how Mono’s API didn’t just connect to a bank; it created a smooth, almost invisible, bridge for the user. It was clear then that they weren’t just another API provider; they were building the foundational plumbing for the future of finance in Africa. The all-stock deal is a direct reflection of that shared vision. This isn’t just Flutterwave buying a service; it’s a deep, structural alignment. It ensures that Mono’s team is now fundamentally invested in our collective success, turning a partnership into a shared destiny.
Flutterwave states Mono will operate independently, emphasizing “strategic alignment rather than operational control.” Can you walk us through the day-to-day mechanics of this arrangement? How will you balance Mono’s independent innovation while contributing its open banking infrastructure to Flutterwave’s broader ecosystem?
Think of it as nurturing a specialist within a larger family. On a daily basis, Mono’s leadership and team in Lagos will continue to do what they do best—innovate at a rapid pace without us looking over their shoulder. The magic happens at the strategic intersection. We bring them into conversations about the massive challenges we’re solving across our ecosystem, which has already processed over one billion transactions, and they can architect solutions using their deep expertise. It’s about giving them the freedom to build the best engine possible while we work together on designing the revolutionary vehicles it will power. This way, their agility is preserved, and our entire ecosystem benefits from their cutting-edge infrastructure.
Your CEO, Olugbenga Agboola, stated that Africa’s future payments growth will be driven by bank-based methods, not card rails. Beyond faster onboarding, what are some tangible, step-by-step examples of how this open banking infrastructure will change a user’s everyday financial experience in the next year?
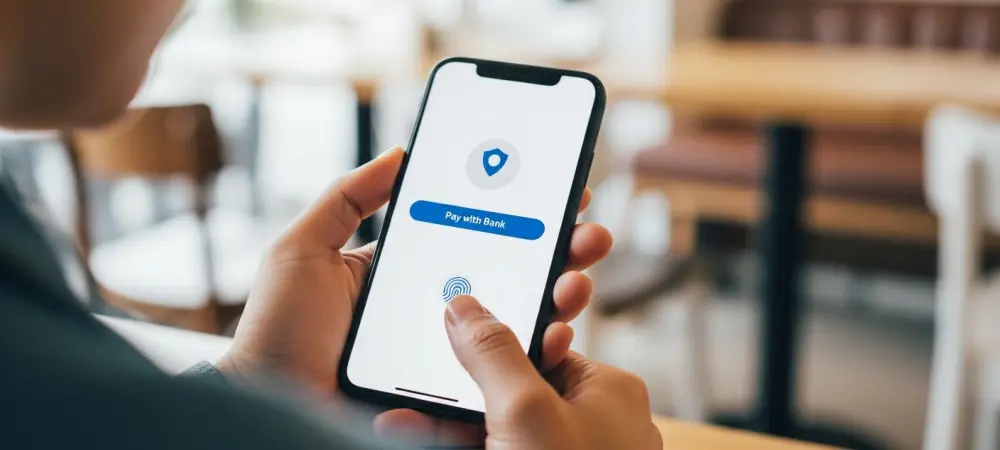
Absolutely. The change will feel incredibly intuitive. Imagine you’re signing up for a new digital service. Instead of manually typing in account details and waiting for small verification deposits, you’ll simply grant permission through your banking app, and you’re verified and onboarded in seconds. When you’re at an online checkout, you won’t need to hunt for your wallet to enter a 16-digit card number and CVV. You’ll just choose “Pay with Bank,” authenticate with your fingerprint in your banking app, and the payment is done. It’s not just faster; it’s a leap in security and trust, as the authentication happens directly with the institution you already trust your money with—your bank.
The announcement mentions a pathway toward authenticated payment flows and open banking-enabled stablecoin use cases. Could you detail the technical or regulatory milestones needed to achieve these innovations, and how does acquiring Mono’s API platform for over 50 banks specifically accelerate that timeline?
To bring these innovations to life, the journey involves both technical and regulatory steps. For authenticated payment flows, the key is achieving a critical mass of bank participation and regulatory comfort, creating a standardized, trusted network. By acquiring Mono, we’ve essentially jumped years ahead on the technical front. Building secure, reliable API connections to over 50 banks is a monumental task that they’ve already accomplished. For stablecoin use cases, the challenge is creating a seamless bridge between the traditional banking world and the digital asset space. Mono’s infrastructure provides the perfect on-ramp and off-ramp, allowing users to move value from their bank account to a stablecoin and back with full authentication. This acquisition gives us the foundational layer to build these next-generation products on.
What is your forecast for the adoption of open banking across Africa in the next five years, especially considering the different regulatory environments from Nigeria to other emerging markets?
My forecast is for a rapid, but market-by-market, explosion in adoption. Nigeria, thanks to innovators like Mono, is already setting the pace and creating a powerful proof of concept. Over the next five years, I expect to see a domino effect as regulators in other major African economies witness the immense benefits—from enhanced financial inclusion to superior fraud prevention and a thriving digital economy. We won’t see a one-size-fits-all pan-African mandate, but rather a wave of localized, intelligent regulation that learns from the Nigerian experience. The move away from legacy card rails is a foregone conclusion; open banking is the connective tissue for the future, and it will become the dominant payment infrastructure across the continent’s key hubs within this period.