

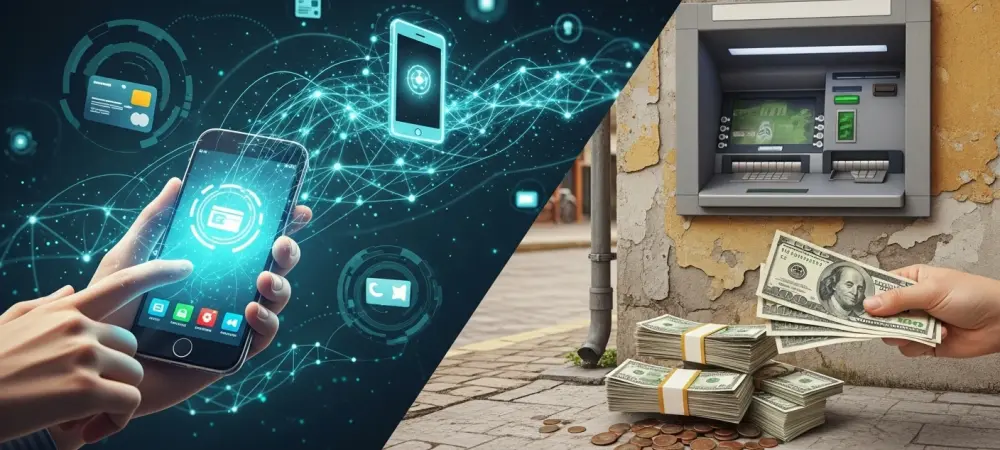
The familiar tap of a card or scan of a smartphone has become so routine for many that it is easy to overlook the growing chasm it creates, leaving millions without a reliable way to participate in the economy. This seemingly simple evolution in how we pay for goods and services masks a complex societal tug-of-war between the undeniable convenience of digital transactions and the foundational necessity of physical cash.
The Evolving Landscape of Commerce: Digital Surge and Cash Persistence
The global momentum toward digital payments is undeniable, with countries like Australia serving as a prime example of this rapid transformation. Over the past several years, the use of mobile wallets has surged an astonishing 23-fold, signaling a profound shift in consumer behavior. This digital wave promises efficiency, speed, and a wealth of data that can drive economic innovation.
However, this technological advancement has not rendered physical currency obsolete. For millions of people, cash remains an indispensable tool for daily life. Vulnerable and marginalized populations, in particular, depend on it for budgeting, privacy, and basic economic participation. The persistence of cash highlights a critical conflict: how to embrace the benefits of a digital future without abandoning those who rely on the tangible security of the present.
A Tale of Two Systems: Key Differences in Function and Impact
User Demographics and Accessibility
The user bases for digital payments and cash access are starkly different, revealing a deep societal divide. Digital systems are primarily embraced by tech-savvy individuals who have consistent access to banking services, smartphones, and reliable internet. They represent a large and growing segment of the population that values convenience and integration. In sharp contrast, an estimated 1.5 million Australians and 4.5% of unbanked households in the United States continue to depend on physical cash. This group often includes the elderly, residents of rural areas, low-income individuals, and people with disabilities. For them, factors like digital literacy, affordability of technology, and distrust in financial institutions make cash not just a preference but a necessity.
Infrastructure and Availability
The two systems are supported by entirely different infrastructures. Digital payments operate on a vast, invisible network of servers, internet connections, and mobile technology that facilitates instantaneous transactions. This ecosystem is constantly expanding, driven by private sector innovation and consumer demand.
Cash, on the other hand, relies on a tangible, physical infrastructure of bank branches and ATMs. This network is rapidly contracting as a direct consequence of the digital shift. Since 2011, Australia has witnessed a 50% reduction in bank branches and a significant decline in fee-free ATMs, making it increasingly difficult and costly for people to access their own money.
Economic Impact and Financial Inclusion
The broader economic implications of each system diverge significantly. The digital economy is characterized by its efficiency and data-rich environment, which can inform business strategies and economic policy. Transactions are traceable, streamlined, and integrated into a global financial network.
Meanwhile, cash serves a crucial role in ensuring privacy and universal economic participation. It is a public good that requires no third-party approval, making it accessible to everyone, regardless of their financial history or status. The decline in cash access, therefore, creates tangible barriers, effectively isolating certain populations from essential economic activities and threatening to build a two-tiered system of financial inclusion.
Navigating the Divide: Societal Challenges and Regulatory Hurdles
The primary challenge emerging from this rapid, and often unregulated, transition to a cashless society is the risk of widespread financial exclusion. As businesses increasingly favor digital-only payments, those who rely on cash find themselves unable to purchase essential goods and services, deepening existing inequalities.
In response, governments are beginning to intervene, but these efforts face their own hurdles. Legislative proposals like the U.S. Payment Choice Act, which would mandate cash acceptance for many transactions, place new burdens on merchants who have adapted to a digital model. Similarly, state-level initiatives must balance consumer protection with the practicalities of business operations, highlighting the difficulty of retrofitting inclusivity into an economy that has already moved on. This creates a difficult balancing act for policymakers, who must find a way to encourage financial innovation while upholding the fundamental right of all citizens to access basic payment methods.
Forging a Balanced Future: Policy Interventions and Recommendations
The analysis reinforces a clear conclusion: while digital payments offer powerful convenience for the majority, their unchecked dominance threatens to disenfranchise a significant minority. This realization has spurred a variety of regulatory solutions aimed at preserving the role of cash in a digital age.
A comparative look at these solutions reveals different philosophical approaches. In the U.S., proposals have centered on mandating cash acceptance, compelling businesses to accommodate all customers. Australia, facing a more acute decline in physical infrastructure, is exploring more systemic interventions. These include a mandate requiring essential service providers to accept cash by 2026, as well as more foundational ideas like classifying banking as an essential service to guarantee physical access or even establishing a public bank to directly serve marginalized communities. These differing strategies underscored a shared recognition that market forces alone would not protect financial inclusion. Ultimately, a hybrid financial ecosystem, supported by deliberate and thoughtful government regulation, was necessary to ensure cash remained a viable and accessible option for everyone.