

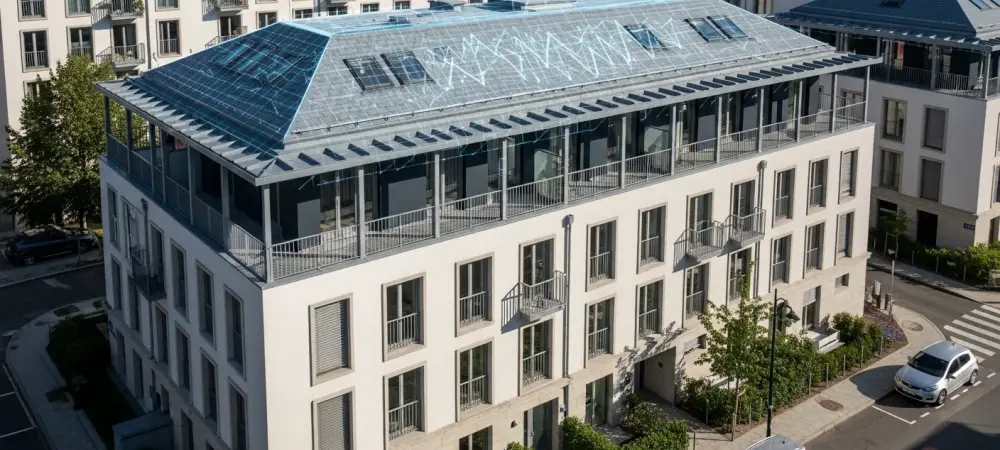
The traditional commercial insurance model has long been anchored by physical inspections and static actuarial tables, yet a new wave of deep-tech platforms is fundamentally dismantling these antiquated constraints through granular data ingestion. This transition marks the end of an era where risk was calculated using broad strokes and neighborhood averages, replacing it with a precise building-by-building analysis.
The Evolution of Deep-Tech Underwriting in Commercial Real Estate
AI-native underwriting departs from the laborious “boots on the ground” approach. Instead of sending an inspector to every site, platforms use computer vision to assess risks instantly, eliminating much of the human error inherent in manual categorization. This shift allows for the processing of applications in minutes rather than weeks.
Legacy carriers often rely on broad data, which punishes high-quality assets in lower-tier neighborhoods. In contrast, deep-tech systems prioritize the physical reality of the structure, ensuring that the policy reflects the actual building rather than its neighbors. This addresses the long-standing inefficiency where well-maintained properties were overcharged to subsidize high-risk neighbors.
Core Pillars of the AI-Native Technological Framework
Granular Data Ingestion and Building-Level Analysis
High-resolution satellite imagery serves as the foundation for building-level analysis. These systems digest hundreds of variables, from roof conditions to the proximity of fire hazards. By moving beyond zip-code averages, the technology rewards property owners who invest in maintenance with lower premiums that were previously unavailable.
Proprietary Machine Learning Models for Risk Pricing
Proprietary models represent a paradigm shift for older urban assets. Many traditional insurers reject buildings over a certain age regardless of their condition. AI-native models distinguish a renovated brick apartment from a decaying structure. This technical nuance allows for higher accuracy in risk distribution and fairer pricing across the market.
Emerging Trends in the AI-Native Insurance Sector
A clear divide exists between “AI-added” and “AI-native” operations. While incumbents patch legacy systems with digital tools, newcomers build their entire infrastructure around data-first logic. This architectural difference allows for a lean operational footprint and rapid scalability that legacy firms cannot match.
Real-World Applications in the U.S. Property Market
Deployment across over 20 states has proven the scalability of this model in the American multi-family housing market. With over $100 billion in insured assets, these platforms are significant participants. Growth suggests that property owners are eager for faster onboarding and reduced transaction friction.
Technical Hurdles and Market Obstacles
Regulatory compliance remains a barrier as each state maintains unique insurance laws. Ensuring the precision of environmental data across diverse climates also poses a challenge. Models must account for specific regional risks, demanding constant retraining and expanding data sources to maintain accuracy.
The Future of Digital Property and Casualty Insurance
Focus now shifts toward total geographic coverage across the country. Diversification into other commercial niches, such as shopping centers, seems inevitable as the data models mature. This trajectory will redefine the carrier relationship, moving toward a data-driven partnership rather than a purely transactional one.
Assessment of the AI-Native Underwriting Landscape
The rise of AI-native underwriting signaled a turning point for the industry. The removal of manual inspections proved to be more than a convenience; it was a fundamental shift in risk science. Platforms like Honeycomb demonstrated that digital-first models could outperform traditional firms in both speed and accuracy. Ultimately, the industry moved toward a future where data, not intuition, dictated the value of security.