

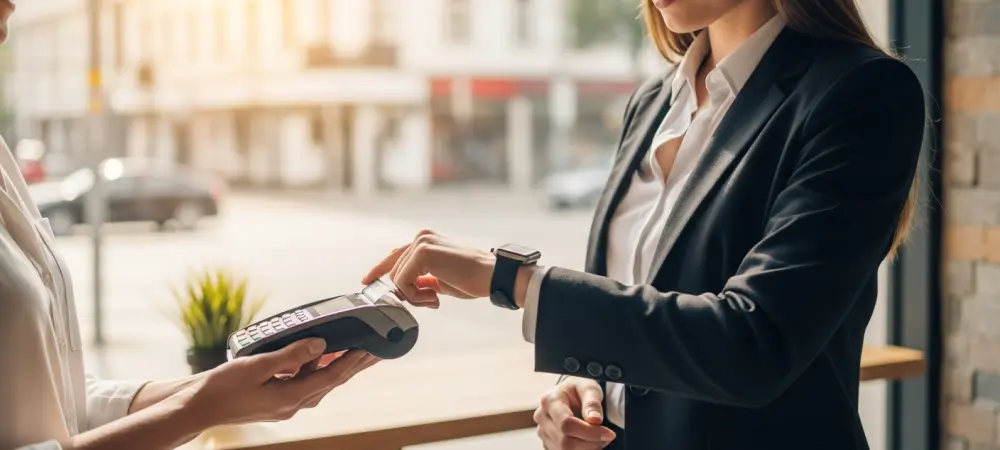
The physical exchange of paper currency and the clinking of coins in pockets are rapidly becoming relics of a bygone era as Botswana’s financial landscape undergoes a profound transformation into a digital-first ecosystem. This evolution is not merely a change in consumer habits but a strategic realignment of the national economy toward higher efficiency and broader accessibility for all citizens. At the center of this movement is the introduction of advanced mobile payment solutions that turn everyday smartphones and wearables into sophisticated financial tools. By removing the traditional barriers associated with physical banking, these technologies are bridging the gap between urban centers and rural communities. The rapid adoption of these tools reflects a societal readiness to embrace modernization, driven by a desire for faster transactions and enhanced security protocols. As the nation pivots away from the limitations of cash, it paves the way for a more resilient and inclusive financial future that prioritizes user experience and technological integration.
Consumer Experience: Transitioning to Digital Wallets
The transition from carrying bulky wallets filled with plastic cards to the sleek efficiency of a smartphone represents a fundamental shift in how residents of Botswana interact with their money. Near Field Communication technology has become the primary driver of this change, allowing users to complete transactions with a simple tap of their devices. This move toward digital wallets effectively eliminates the need for physical contact with point-of-sale terminals, which has become a preferred method for those seeking both speed and hygiene in their daily lives. By utilizing hardware that consumers already carry, such as Android phones and smartwatches, the financial sector has lowered the barrier to entry for digital adoption. This convenience extends beyond simple payments, as it integrates financial management directly into the mobile devices that have become central to modern life. The resulting behavioral change indicates a growing public confidence in technology to handle sensitive fiscal matters reliably. To further cement this digital transition, the integration of local banking services with established global platforms like Google Pay and Garmin Pay provides a necessary layer of interoperability. This flexibility allows users to select the interface that best suits their individual preferences while maintaining the robust security of their underlying bank accounts. Such collaborations ensure that the financial infrastructure can manage significant increases in transaction volume without compromising on speed or reliability. High-performance backend systems work behind the scenes to process these taps instantly, fostering a level of trust that is essential for a cashless society to thrive. When consumers know that their payment will go through every time they reach for their phone, they are far less likely to revert to carrying emergency cash. This reliability is the bedrock upon which a truly digital economy is built, ensuring that the movement away from physical currency is permanent and sustainable for both merchants and shoppers across the country.
Security Protocols: Protecting the Digital Frontier
Security remains the most critical concern for any nation transitioning to a cashless system, and the deployment of multi-layered defense strategies has been paramount in addressing these risks. One of the most effective innovations currently in use is the implementation of dynamic Card Verification Value codes, which change at regular intervals within the mobile banking application. This ensures that even if a bad actor manages to capture card information during a transaction, the data becomes worthless almost immediately because the verification code expires. Furthermore, tokenization technology replaces sensitive account details with unique digital identifiers, meaning that actual card numbers are never stored on the merchant’s device or transmitted over the network. These sophisticated measures provide a level of protection that physical plastic cards simply cannot offer, as they are inherently vulnerable to skimming and theft. By making fraud significantly more difficult to execute, these technologies protect the integrity of the entire ecosystem.
Beyond automated defense mechanisms, the current financial landscape emphasizes user empowerment through advanced biometric authentication and real-time administrative controls. Gone are the days when losing a wallet meant hours of stressful phone calls to cancel cards; users can now freeze or unfreeze their accounts instantly through a mobile interface. Biometric markers, such as fingerprint and facial recognition, ensure that only the authorized owner of the device can execute a transaction, adding a personal layer of safety that passwords often lack. Additionally, the ability to generate virtual cards for one-time or recurring online use allows customers to shield their primary accounts from potential e-commerce vulnerabilities. This instant service delivery means that consumers can start transacting immediately without waiting for a physical card to be mailed or collected from a branch. These tools collectively transform the mobile phone into a secure personal control center, giving citizens unprecedented transparency and authority over their financial security at all times.
Strategic Implementation: Lessons for a Cashless Economy
The historical shift toward a cashless economy in Botswana necessitated a robust partnership between the public and private sectors to ensure widespread infrastructure readiness. Financial institutions successfully collaborated with telecommunications providers to expand network coverage, which allowed even remote areas to participate in the digital banking revolution. Regulators played a vital role by establishing clear frameworks that protected consumer rights while encouraging the growth of innovative fintech startups. Businesses were encouraged to modernize their hardware to support contactless payments, thereby creating a seamless environment for the tap-to-pay culture to take root among the general population. Between 2026 and 2028, these coordinated efforts transformed the national payment landscape from one reliant on physical currency to a model of digital efficiency and security. The focus then shifted toward continuous education programs that helped citizens understand the benefits and safety of mobile wallets. Strategic investments in cybersecurity infrastructure proved to be a decisive factor in maintaining long-term public confidence in the digital banking system. Policymakers and bank leaders prioritized the development of standardized protocols that allowed different platforms to communicate with one another without friction. This commitment to open banking enabled a more competitive market where service providers constantly improved their offerings to attract and retain customers. Furthermore, the integration of real-time data analytics provided banks with deeper insights into consumer behavior, which allowed for the creation of more personalized financial products and services. The resulting ecosystem empowered the workforce by providing easier access to credit and formalizing many sectors of the economy that were previously difficult to monitor. These milestones marked a significant turning point in the nation’s development, setting a high standard for how a country could successfully modernize its financial heart while ensuring that no demographic was left behind.