

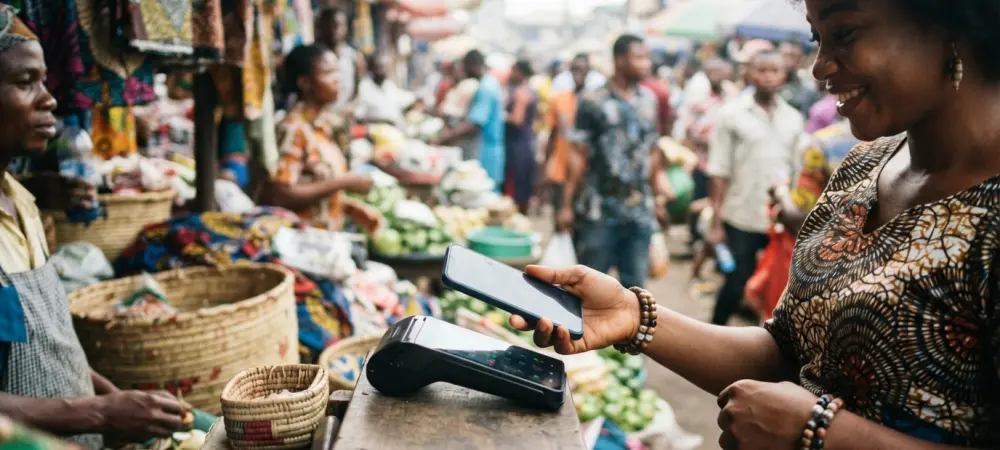
Jimmy Banjoko of GTBank observes that the widespread existing use of banking applications has already prepared the Nigerian market for a rapid shift to tap-based commerce. This transition signifies more than just a technical convenience; it represents a fundamental overhaul of how value is exchanged across the continent. As Interswitch collaborates with major financial institutions, the traditional reliance on physical plastic cards is fading in favor of a digital-first approach. The landscape is moving away from the cumbersome nature of manual bank transfers, which often require multiple authentication steps and long wait times, toward the immediate gratification of a physical tap. This evolution is driven by a necessity to match the speed of global finance while addressing local logistical challenges. By embedding Near Field Communication technology into the daily routines of millions, Nigeria is effectively bypassing the limitations of older payment infrastructure.
Secure Foundations: The Mechanics of Tokenized Transactions
Tokenization serves as the invisible engine driving this transformation, offering a sophisticated security protocol that effectively decouples a customer’s sensitive financial data from the actual point of transaction. By replacing the sixteen-digit primary account number with a unique, non-sensitive digital identifier known as a token, the system ensures that the merchant never receives the actual card details. This mechanism is crucial because it significantly limits the potential damage from a data breach at the merchant level. If a token is intercepted, it remains useless to a malicious actor because it is restricted to a specific device or transaction type. This approach naturally leads to a more resilient financial ecosystem where trust is maintained through technical barriers rather than just administrative oversight. The deployment of these tokens across thousands of merchant locations from 2026 to 2028 will serve as the backbone for the next generation of secure, contactless commerce.
Building on this foundation of data security, the integration of biometric verification adds a second layer of defense that makes the tap-to-pay model far superior to traditional methods. When a consumer initiates a payment via a smartphone or a wearable device, the transaction is often authorized through facial recognition or fingerprint scanning integrated into the hardware itself. This ensures that even if a device is lost or stolen, the financial assets of the user remain inaccessible to unauthorized parties. This multi-layered defense mechanism is particularly relevant in the Nigerian context, where digital fraud has historically been a significant concern for both consumers and banking executives. By making the security process nearly instantaneous and inherently personal, the technology addresses the psychological barriers to digital adoption. The goal is to move beyond the era of vulnerable PIN codes and static passwords toward a system where identity and payment are inextricably linked through secure, biological identifiers.
Enhancing Commercial Velocity: Eliminating Transactional Friction
Akeem Lawal, the Managing Director of Purepay at Interswitch, emphasizes that the primary obstacle to digital payments has always been friction. Currently, most Nigerians who wish to pay digitally must navigate a multi-step process that involves unlocking a device, opening a banking application, typing in recipient details, and waiting for several confirmation screens to clear. The shift to tap-to-pay is specifically designed to collapse these fragmented steps into a single, seamless motion that takes less than a second to complete. By removing these technical and cognitive hurdles, Interswitch and its partners are not just improving a service; they are increasing the overall velocity of commerce within the country. Faster checkout lines and reduced processing times directly translate to higher turnover for merchants and a more satisfying experience for consumers. This efficiency is necessary to support a modern economy.
The utility of this contactless technology must extend beyond high-end retail to achieve true ubiquity within the urban infrastructure. Tunde Mabawonku, an Executive Director at Wema Bank, has highlighted the importance of integrating tap-to-pay systems into the public transportation networks of major cities. Specifically, the expansion into the Lagos Bus Rapid Transit system and the newly operational rail lines provides a massive use case for tokenized payments. Imagine a daily commuter who can board a bus, pay for a train ride, and purchase a meal using the same smartwatch or smartphone without ever reaching for a wallet. This level of integration embeds financial services into the very fabric of daily life, making the technology indispensable rather than optional. Furthermore, the push into wearables like fitness trackers and smart rings suggests that the future of payment is hands-free. This shift toward the Internet of Things allows for a truly connected financial life where every interaction is as simple as a gesture.
Future Outlook: Achieving Widespread National Adoption
Achieving national adoption requires more than just consumer interest; it demands a comprehensive upgrade of the physical infrastructure across the country. For the tap-to-pay ecosystem to function effectively, merchants ranging from large supermarkets to small-scale street vendors must have access to Point-of-Sale terminals equipped with Near Field Communication technology. Simultaneously, financial institutions are working to ensure their backend systems are fully compatible with digital wallets and tokenization standards. This technical alignment is a massive undertaking that involves coordinating with international card schemes and local regulatory bodies to ensure a unified standard. Moreover, the pace of this transition is closely tied to the availability of affordable, NFC-enabled hardware for the general population. While high-end devices are already common, the mass market relies on budget smartphones. Ensuring that these devices include the necessary chips is vital for bringing the benefits of tokenized payments to everyone.
The transition toward a post-card economy defined the strategic priorities of Nigeria’s financial leaders as they sought to modernize the national market. To maintain this momentum, banks and payment processors focused on scaling the availability of NFC-ready terminals to rural and underserved regions, ensuring that no geographic area was left behind in the digital shift. The development of unified standards for digital wallets allowed for greater interoperability between different banking platforms, which encouraged widespread merchant acceptance. Looking forward, the focus turned toward the education of small-scale entrepreneurs regarding the security benefits and cost efficiencies of contactless systems. Stakeholders also prioritized the creation of local manufacturing incentives for affordable NFC-enabled devices to reduce the cost of entry for the average consumer. By treating payment technology as a public utility rather than a luxury, the industry established a robust framework that successfully integrated financial services into the infrastructure of the future.