

Analyze the content of the provided article and identify the key points or most critical information that summarize the core message.Highlight the most important sentences in Markdown as follows: most important sentences to ensure clarity and emphasis.
The ability of Western innovators to bypass hardware bottlenecks will determine which nation leads the next generation of industrial and consumer automation. As humanoid robots transition from laboratory prototypes to commercial entities on factory floors, a stark reality has emerged: the physical infrastructure required to build these machines is heavily concentrated in a few geographic clusters. Western developers, while excelling in artificial intelligence and complex control algorithms, frequently find themselves at the mercy of specialized component manufacturers located thousands of miles away. This structural dependency is not merely a logistical inconvenience but a strategic vulnerability that threatens the autonomy of the burgeoning robotics industry. Escalating trade tensions and restrictive export controls are forcing a re-evaluation of globalization practices. For companies aiming to deploy thousands of units, the challenge is about securing a reliable hardware pipeline that can withstand geopolitical shocks.
The Persistent Grip: Integrated Supply Ecosystems
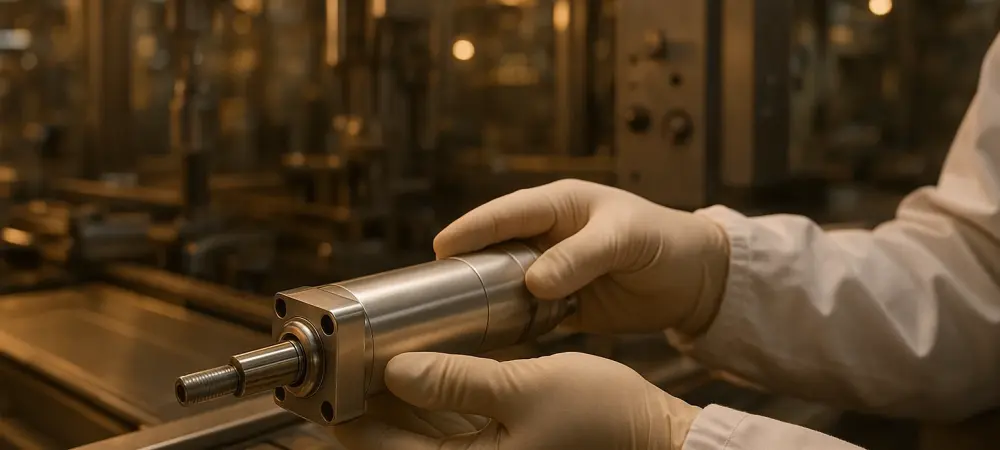
China’s current command over the humanoid robotics supply chain is the result of decades spent building a tightly integrated manufacturing base that caters specifically to precision engineering. This dominance is most evident in the production of harmonic drive reducers and high-torque density motors, which serve as the essential joints and muscles of any humanoid system. Unlike generic electronics, these mechanical parts require specialized metallurgical processes and extreme precision that cannot be replicated overnight. The existing clusters in regions like Shenzhen benefit from an economy of scale and a shared talent pool that allows for rapid prototyping and iterative improvements at a fraction of the cost found in Western markets. For a Western startup, sourcing these components from domestic suppliers often means dealing with lead times that are double those of Chinese counterparts, creating a significant barrier to entry for those attempting to maintain a competitive pace in a rapidly evolving market.
The challenge for Western manufacturers is further compounded by the lock-in effect created by customized component specifications. Humanoid robots are not yet standardized products; every design uses unique actuators and sensors that must be rigorously validated for durability and performance. Once a design is optimized for a specific Chinese motor or reducer, switching to a different supplier often necessitates a fundamental redesign of the robot’s physical architecture. This process is both expensive and time-consuming, involving months of reliability testing and software recalibration to accommodate the new hardware’s performance profile. Consequently, many Western firms find themselves tethered to their current suppliers out of technical necessity rather than just cost-efficiency. This deep integration makes the prospect of de-coupling a monumental engineering task that extends far beyond simple procurement changes, requiring a total overhaul of the manufacturing strategy and long-term financial commitments from various stakeholders.
National Policy: Addressing the Strategic Robotics Gap
One of the most persistent obstacles facing Western innovation is the lack of a cohesive, state-level strategy comparable to those found in competing nations. While the United States and several European countries have been aggressive in implementing trade restrictions on foreign technology, they have been slower to introduce the robust industrial policies needed to fill the resulting void. In contrast, international competitors have treated humanoid robotics as a national priority, providing significant tax breaks, research grants, and guaranteed government contracts for domestic component makers. This top-down approach has created a predictable environment for investors and has allowed local hardware companies to scale their operations with confidence. In the West, however, the robotics industry remains largely driven by private venture capital, which is often more interested in software-driven returns than the capital-intensive reality of hardware manufacturing. Without a unified policy framework to drive domestic demand, the West risks remaining in a reactive stance. The absence of a domestic demand engine is perhaps the most significant hurdle for Western component manufacturers. To compete with the pricing of established global hubs, manufacturers must produce parts in massive quantities, which requires a stable and growing market for their products. Currently, many domestic hardware startups struggle to find enough local customers to justify the massive investment needed for high-volume production facilities. This creates a circular problem: without a domestic supply chain, robot makers buy from overseas; without domestic buyers, the supply chain cannot afford to expand. Solving this demand problem will likely require more than just subsidies; it will necessitate a cultural shift toward the early adoption of automation in local industries. Government-backed pilot programs in healthcare, logistics, and defense could provide the necessary initial scale to help domestic suppliers reach a tipping point where they can compete on their own merits without the constant need for trade protection measures.
Technical Excellence: The Road to Future Resilience
While the hardware bottleneck is a significant challenge, it is important to recognize that the West maintains a commanding lead in several critical areas of robotic development. The most advanced humanoid control systems, visual recognition models, and natural language processing interfaces are predominantly developed by Western research labs and technology giants. This software edge allows Western robots to perform tasks with a level of autonomy and safety that is difficult for rivals to replicate. The long-term goal is to leverage this high-level intelligence to compensate for current hardware limitations or to drive the development of entirely new classes of actuators that are easier to manufacture domestically. For instance, the move toward soft robotics and muscle-like synthetic actuators could bypass the need for traditional gearboxes and motors entirely. By focusing on the next generation of hardware rather than playing catch-up with traditional mechanical designs, the West may find a way to leapfrog the existing supply chain crisis altogether.
The path toward a self-reliant humanoid robotics ecosystem demanded a radical departure from the short-term financial thinking that characterized previous years. Western innovators navigated this transition by prioritizing deep technical integration between their hardware and software teams, ensuring that any component shifts were handled with surgical precision. Governments eventually stepped in to provide the necessary fiscal framework, fostering a manufacturing environment where domestic suppliers finally reached the scale required for global competitiveness. The crisis served as a critical wake-up call, forcing a return to industrial fundamentals that had been neglected for too long. By the time the industry matured, the focus shifted from merely surviving supply disruptions to establishing a new standard for robotic quality and ethical manufacturing. The result was a more resilient, transparent, and technologically advanced landscape that secured the West’s role as a leader in the age of industrial and consumer automation during the latter half of the decade.