

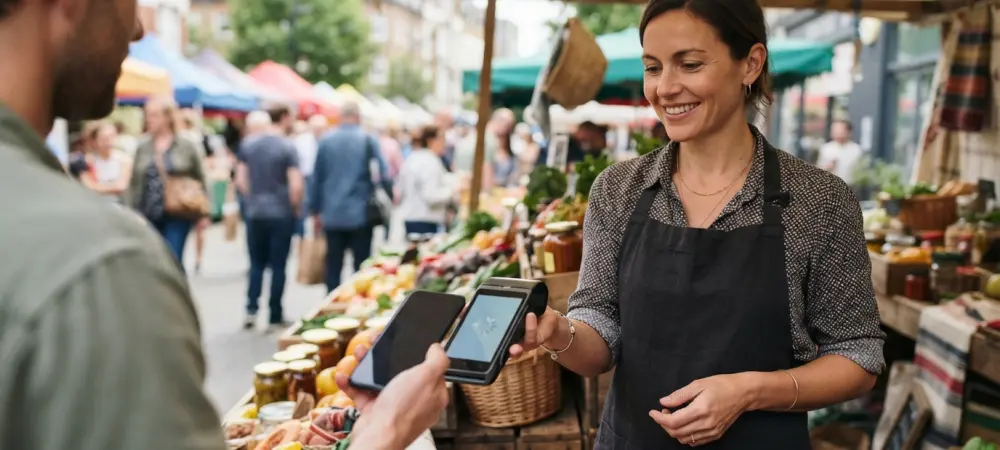
Morocco’s young and tech-savvy demographic is driving a shift toward mobile commerce, though technical availability must still be matched by consumer trust and education. The Moroccan financial sector has reached a defining threshold where traditional banking methods are converging with high-end mobile technology to create a more fluid economic environment. This transformation is being catalyzed by the introduction of Samsung Pay, a platform that leverages the widespread presence of Galaxy devices to provide a secure alternative to physical cash. The partnership between Samsung Electronics Maghreb Arab and Mastercard represents a calculated effort to bypass the limitations of legacy systems in favor of a modern, encrypted ecosystem. By focusing on the Maghreb region, these global entities are identifying Morocco as a critical hub for digital growth in North Africa. As the nation prepares for a future where digital wallets are the norm, the emphasis remains on creating a resilient infrastructure that can support millions of daily micro-transactions with absolute reliability.
Advanced Security: The Role of Tokenization
At the technical heart of this digital evolution lies the Mastercard Digital Enablement Service, commonly known as MDES, which functions as the primary security layer for mobile transactions. This sophisticated platform utilizes tokenization to replace sensitive sixteen-digit credit card numbers with unique digital identifiers. When a Moroccan consumer adds their card to Samsung Pay, the actual account details are never stored on the device or shared with merchants during the payment process. Instead, a specific token is generated for that unique device, ensuring that the original financial credentials remain isolated from potential threats. This approach fundamentally changes the risk profile of mobile payments, as even a successful interception of transaction data would yield nothing but a useless string of numbers. By prioritizing this high-level encryption, the initiative addresses the technical requirements of modern banking while providing a foundation of safety that is essential for gaining widespread public acceptance.
Beyond the core encryption process, the tokenization model integrates advanced authentication protocols that require a user’s biological verification, such as a fingerprint or iris scan, before a transaction is authorized. This multi-layered security architecture ensures that the digital wallet is far more secure than a physical one, which can be easily lost or stolen without any built-in safeguards. In the event that a smartphone is misplaced, the digital tokens can be instantly deactivated without requiring the user to cancel their physical credit cards. This flexibility provides a level of control that was previously unavailable to the average consumer, making the transition to digital finance a matter of both safety and convenience. Furthermore, the risk-based monitoring systems built into the MDES platform continuously analyze transaction patterns to detect and block suspicious activity in real-time. For the Moroccan market, this means that the shift toward mobile commerce is backed by the same rigorous security standards found in the most advanced financial markets.
Strategic Vision: Mastercard’s Global Mandate
The rollout of Samsung Pay in Morocco is a vital component of a much larger global strategy directed by Mastercard to achieve total tokenization of all online transactions by 2030. This ambitious mandate is designed to eliminate the vulnerabilities inherent in manual card entry and legacy payment systems that rely on static data. By targeting the Moroccan market in 2026, Mastercard is demonstrating its commitment to bringing emerging economies into the fold of its worldwide security standards. The transition is not merely about replacing plastic cards with phone screens; it is about creating a unified, global payment grid where every interaction is encrypted and authenticated. This strategic foresight ensures that Morocco’s digital economy is built on a scalable framework that can easily integrate future innovations, such as blockchain-based assets or decentralized finance protocols. By aligning local infrastructure with international goals, the partnership ensures that Moroccan consumers can participate in global commerce without the friction often associated with cross-border payments.
Mastercard’s leadership has consistently emphasized that the future of the financial industry is defined by the three pillars of choice, convenience, and confidence. The Moroccan initiative serves as a successful blueprint for how these values can be exported to other North African territories where cash still plays a dominant role. By establishing a standardized and secure environment, the company is effectively raising the bar for the entire regional industry, forcing competitors to rethink their own security measures and user interfaces. This move creates a ripple effect throughout the local banking sector, as domestic institutions must now accelerate their own digital transformation projects to remain compatible with international standards. The long-term impact of this strategy is a more cohesive and transparent financial system that reduces the informal economy and provides the state with better data for economic planning. Consequently, the push toward tokenization is as much a socio-economic project as it is a technological one, aiming to elevate the entire financial ecosystem.
Hardware Integration: Samsung’s Ecosystem Strategy
For Samsung Maghreb Arab, the introduction of this payment platform represents a sophisticated maneuver to deepen customer loyalty within a highly competitive smartphone market. In an era where hardware specifications such as processor speed and camera quality have largely reached a plateau of parity among manufacturers, the true differentiator has shifted toward ecosystem value. By transforming a Galaxy smartphone or wearable device into a secure and indispensable financial tool, Samsung is providing a compelling reason for Moroccan consumers to remain dedicated to its hardware. This integration creates a high switching cost for users, as the convenience of a pre-configured digital wallet makes it less likely for them to transition to a rival brand. This strategy is particularly effective among the younger demographic, who prioritize seamless digital experiences and integrated lifestyle tools over traditional hardware metrics. By becoming a central part of the user’s daily financial life, Samsung secures its position as a dominant technology provider.
The technical implementation of this strategy relies heavily on Near Field Communication technology, which enables the intuitive tap-to-pay functionality that has become standard in global commerce. A significant advantage of the Samsung Pay launch in Morocco is its immediate compatibility with the existing retail infrastructure. Unlike previous digital payment attempts that required merchants to install proprietary hardware, Samsung’s use of standardized NFC protocols ensures that most modern Point of Sale terminals in the country can accept these payments without modification. This plug-and-play capability is essential for rapid market penetration, as it removes the financial burden from small and medium-sized enterprises that might otherwise be hesitant to adopt new technologies. Furthermore, the ability to store loyalty cards and transit passes within the same secure environment adds another layer of utility for the consumer. This multi-faceted approach ensures that the smartphone is no longer just a communication device, but a universal key that simplifies daily commerce.
Economic Shifts: Bridging the Digital Divide
The demographic profile of Morocco, characterized by a large population of young individuals who are inherently comfortable with technology, provides the ideal foundation for a mobile commerce revolution. However, the transition from a cash-dominated society to a digital one requires more than just high-end devices; it necessitates a comprehensive educational effort to bridge the existing digital divide. Mastercard and Samsung have recognized this challenge by launching joint marketing campaigns that focus on digital literacy and the practical safety of mobile wallets. These initiatives are designed to demystify complex concepts such as tokenization and encrypted authentication, presenting them in a way that is accessible to the general public. By addressing common misconceptions and fears regarding cybercrime, these companies are building the digital confidence required for consumers to take the leap into modern finance. This educational groundwork is vital for ensuring that the benefits of digital payments are shared across all segments of society, regardless of their previous banking experience.
Beyond individual convenience, the shift toward a digital economy has profound implications for the velocity of money and the overall transparency of the Moroccan financial system. By bringing unbanked or underbanked populations into a formal digital framework, the Samsung Pay initiative allows for more efficient tracking and processing of domestic transactions. This streamlined commerce can lead to faster economic growth, as the friction associated with physical cash—such as theft, loss, and the cost of transportation—is significantly reduced. From grocery stores to public transport systems, the ability to conduct instant, secure payments improves the daily lives of citizens and enhances the operational efficiency of local businesses. As more Moroccans embrace this technology, the data generated by these transactions can provide valuable insights for policymakers looking to strengthen the national economy. The ultimate goal is to create a more inclusive financial environment where technology serves as an equalizer, providing every citizen with the tools needed to participate.
Competitive Pressures: A Maturing Regulatory Environment
The entry of a major international player like Samsung Pay into the Moroccan market has created an immediate sense of urgency among local financial institutions and competing technology brands. Local banks that have partnered with this initiative are already seeing a competitive edge, as they can offer their clients a modern user experience that rivals the best in the world. This healthy competition is driving a wave of innovation across the domestic sector, as other banks and fintech startups are now forced to accelerate their own digital offerings to keep pace. The presence of global standards in the market ensures that local players cannot settle for subpar security or outdated user interfaces, ultimately benefiting the Moroccan consumer through higher quality services. Furthermore, this competitive pressure is likely to lead to a more consolidated market where only the most secure and efficient platforms survive. This maturation of the fintech sector is a natural step in Morocco’s progression toward becoming a regional leader in financial services.
Moreover, the successful collaboration between international technology firms and Moroccan financial authorities signals a significant maturation of the country’s regulatory environment. The implementation of such a high-security platform requires a clear consensus on digital privacy, data protection, and electronic transaction laws. This partnership suggests that Morocco has established a regulatory framework that is both robust enough to protect consumers and flexible enough to encourage innovation from global leaders. This alignment with international standards makes the kingdom an increasingly attractive destination for other digital services and fintech investments. It sets a high bar for security that domestic payment schemes must now strive to match, potentially leading to a market that is unified by global security protocols rather than fragmented by inconsistent local standards. As the regulatory landscape continues to evolve, the focus will likely shift toward further enhancing cybersecurity protections and ensuring that the digital financial system remains resilient.
Future Outlook: Ensuring Consumer Confidence
The long-term success of mobile payments in Morocco depends heavily on the industry’s ability to maintain a high level of consumer trust through consistent performance and rigorous security. While the technical advantages of tokenization are clear to experts, the average user is primarily concerned with the reliability and safety of their hard-earned money. Therefore, the ongoing narrative surrounding Samsung Pay must continue to emphasize the built-in protection that differentiates it from older, more vulnerable payment methods. By highlighting that card credentials are never shared with merchants, the platform directly addresses the psychological barriers that have historically hindered digital adoption in emerging markets. When consumers perceive their smartphone as a secure digital vault that is safer than a physical wallet, the transition from cash becomes a logical choice rather than a risky experiment. This shift in perception is the ultimate driver for the widespread adoption of mobile commerce, ensuring that the technology becomes a permanent fixture.
Looking ahead, the role of security will only become more prominent as digital payments expand into new areas of daily life, such as government services and utility payments. The MDES platform serves as the technical backbone that allows for this expansion without compromising the peace of mind that consumers require. As the ecosystem grows, the integration of risk-based safeguards and real-time monitoring will be essential for staying ahead of sophisticated cyber threats. The goal is to create a seamless environment where the technology works silently in the background, allowing users to focus on their transactions while the system handles the complexities of encryption and authentication. This focus on safety acts as the ultimate catalyst for change, moving the conversation away from the fear of fraud and toward the benefits of a modern, connected economy. By establishing this high-trust environment today, the partnership between Samsung and Mastercard is laying the groundwork for a future where the Moroccan consumer is fully empowered to navigate the marketplace.
Strategic Progress: The Path to Digital Maturity
The rollout of Samsung Pay in Morocco effectively demonstrated the power of strategic partnerships in modernizing regional financial systems. By combining global payment infrastructure with widespread consumer hardware, the initiative addressed the technical and security concerns that previously limited digital commerce in the Maghreb. Throughout the initial launch phase, the focus remained on establishing a foundation of trust and providing the necessary education to a tech-savvy but cautious population. Local banks and merchants played a critical role in this transition, adopting the new standards and integrating the technology into the daily retail experience. This collaborative effort was instrumental in proving that even a cash-heavy economy could successfully transition to a more efficient and secure digital model. The project was not just a successful product launch; it served as a significant milestone in the kingdom’s journey toward financial modernization and digital inclusion, setting a high standard for future technological deployments.
To maintain this momentum, future efforts should focus on expanding the digital ecosystem to include small-scale vendors and public services, ensuring that the benefits of mobile payments are accessible in every corner of the economy. Financial institutions must continue to prioritize cybersecurity education, providing users with the tools and knowledge to protect their digital identities as threats evolve. The government could further support this transition by offering incentives for digital adoption among small businesses, which would accelerate the formalization of the economy and increase national tax efficiency. As Morocco moves closer to the global goal of total transaction tokenization, the integration of new financial technologies will likely become even more seamless. The success of Samsung Pay provides a clear roadmap for other emerging markets, showing that with the right combination of secure technology and strategic cooperation, the path toward a cardless future is both achievable and beneficial. The smartphone has now become a central pillar of financial freedom.