

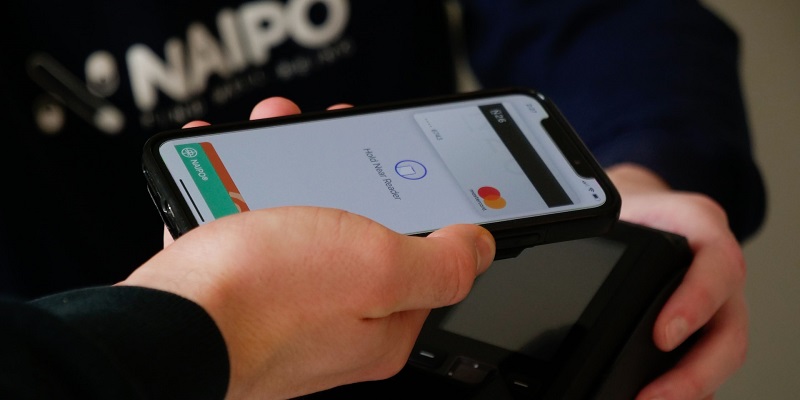
As we move further into the digital age, an increasing number of countries are pushing towards a cashless society. The UK is among these pioneers, following in the footsteps of Norway and Sweden, with sparse usage of cash following the pandemic. The transition was intensified by the need to socially distance during the pandemic, and e-wallets and digital transactions became the norm. As the nation moves towards a greater number of online payment methods, the challenge is to ensure that everyone is included in this shift. In this article, we will explore the challenges and opportunities presented by the move towards a cashless society in the UK.
The pandemic had a profound impact on cash usage in the UK. The need for social distancing accelerated the adoption of digital transactions and e-wallets, as people sought contactless payment methods. The World Economic Forum reports that cash usage has been declining globally for a while, with estimates showing that it could drop by 25% over the next decade. It is worth noting that contactless transactions had already been on the rise in the UK, but the pandemic certainly amplified this shift.
Central Bank Digital Currency (CBDC)
According to the Bank for International Settlements, 90% of central banks are developing plans for central bank digital currency (CBDC) which has the potential to reduce the use of cash. This could help to provide a more secure and stable alternative to traditional payment methods. CBDC is a digital version of a country’s fiat currency, backed by its central bank.
Payments Choice Alliance
While there is much optimism about the move towards a cashless society, there are also challenges. Positioned steadfastly against this shift is the Payments Choice Alliance. The organization demands that every person in the UK should be provided with options for making payments. The alliance is particularly concerned about the rights of low-income earners who may not have access to bank accounts or digital payment methods. They are calling for a Payments Choice Act to address these concerns.
Retailers Providing Multiple Payment Options
Several retailers have been focused on providing consumers with multiple payment options, such as grocery giants Sainsbury’s and Tesco, which both accept cash and often have ATM machines outside their stores. This indicates that retail businesses are keen to ensure that all customers have access to the payment methods they prefer.
Spanish Payment Choice Act
One model that could be adopted in the UK is The Spanish Payment Choice Act, which was introduced in December 2020. The law requires banks to offer consumers a basic bank account that has no associated costs or fees. The account must be offered to anyone who is a legal resident of Spain and who is not already using a payment account. Elements of this legislation could be included in a UK Payments Choice Act.
Potential Impact on General Election
The shift towards a cashless society could become a General Election issue in 2024. Delnevo, a campaigner for the Payments Choice Alliance, has stated that MPs from multiple parties are invested in the cause, and that cash payments could become an election issue in 2024 if a UK Payments Choice Act is not introduced by 2023.
Inclusion of Lower-Income Communities and Older Generations
The move towards a cashless society can impact lower-income communities and older generations disproportionately. People who are not familiar with using digital payment methods need support with their usage and education. Bradbury, a campaigner for a Payments Choice Act, explains that personalization, education, and inclusion need to be phased in the approach. It is essential that the right strategies are implemented to ensure that everyone is included in the cashless system.
Cooperation between Banks, Fintech, and Government
As the nation moves towards an increasing number of online payment methods, it is vital that banks, fintech companies, and the government work together to provide for the needs of the public. Collaboration is essential to ensure that all payment options are available and accessible to everyone.
The move towards a cashless society is inevitable in the UK, as it is in many other countries across the globe. The shift is not without its challenges, and it is essential that everyone is included in the process. The debate around the rights of low-income earners and older generations must be considered, and the Payments Choice Act could be the best way forward. The role of retailers, the potential impact on a general election, and the need for cooperation between banks, fintech, and the government indicate the wide-reaching implications of this change. It is an exciting time for the UK, and the future of payment methods looks fascinating.