

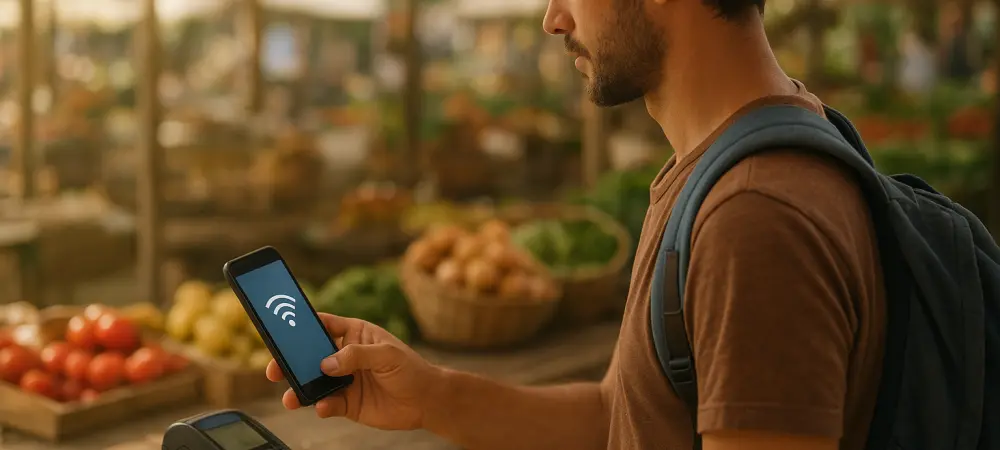
The global economic landscape is undergoing a radical metamorphosis where the boundary between physical presence and digital execution is dissolving into a single, unified experience for the modern traveler. This transition marks the arrival of a frictionless frontier, a state of commerce where a digital wallet no longer serves as a static storage for funds but as an active, intelligent assistant. In this environment, the wallet anticipates individual needs, negotiates exchange rates in real-time, and settles transactions at a local street market halfway across the globe without a single point of friction or manual calculation. Such a vision represents the pinnacle of consumer convenience, where the geographical location of the buyer and the currency of the seller become irrelevant to the speed and efficiency of the trade.
However, a persistent digitalization gap continues to haunt the international commerce sector despite the surge in global travel and digital connectivity over recent years. While consumers are more connected than ever, 54% of individuals still struggle to use their preferred payment methods when crossing borders, revealing a disconnect between technological potential and merchant reality. This discrepancy creates a fragmented experience where the ease of booking a flight online does not translate to the ease of buying a coffee at the destination. The persistence of this gap suggests that the infrastructure supporting global trade has not yet caught up with the high-velocity expectations of a mobile-first generation that views borders as arbitrary hurdles rather than functional barriers.
The path forward requires a deep exploration of the evolution of cross-border commerce, specifically looking at the rise of agentic AI and the critical need for technical interoperability. To create a truly borderless global economy, the industry must move beyond simply providing a platform for transactions to building a cohesive network where different systems can communicate effortlessly. This evolution is not merely a matter of upgrading software but involves a fundamental shift in how trust is established between a traveler from one continent and a local merchant on another. By focusing on the integration of artificial intelligence and the standardization of payment protocols, the sector aims to transform the current fragmented landscape into a seamless, automated, and inclusive marketplace.
The State of Global Digital Commerce and Mobile Adoption
Data Insights: The Growing Demand for Seamless Transactions
Current statistics reveal that the transition to a digital-first lifestyle has left a significant portion of the global population feeling stranded when they leave their home markets. Over 50% of global travelers report facing persistent uncertainty regarding whether their digital payment methods will be accepted at international points of sale. This lack of confidence stems from the inconsistent deployment of digital infrastructure, which varies wildly from city to city and country to country. Research indicates a high digitalization gap where 53% of users remain unsure if their primary mobile wallets will function in foreign markets, leading a striking 25% of travelers to continue relying on physical cash as a mandatory fallback. This reliance on cash highlights a failure in the promise of the digital revolution, as users are forced to revert to legacy systems to ensure their survival and mobility while abroad.
The shift in consumer behavior is further complicated by a massive move toward hyper-local spending, which places additional strain on payment systems that were originally designed for large-scale international chains. Adoption trends show that 67% of consumers are increasing their budgets for local food and beverage experiences over global restaurant brands, seeking authenticity and unique cultural connections. This preference for small, independent vendors means that digital payment interoperability must extend down to the level of the street stall and the family-owned boutique. When a traveler chooses a local attraction or eatery, they often encounter the limits of international banking networks, which are frequently too cumbersome or expensive for the small-scale merchant to adopt, thereby widening the gap between consumer desire and technological capability.
Real-World Applications: From Mobile Wallets to Super Apps
The industry has seen the emergence of unified gateways as a primary solution to these challenges, with Ant International’s Alipay+ serving as a leading example of how to bridge the gap. By connecting 2 billion user accounts across 50 payment partners, such platforms allow local vendors to accept a vast array of international digital wallets without needing to overhaul their existing hardware. This approach effectively turns a local merchant’s simple payment terminal into a global point of sale, ensuring that a tourist from a QR-centric region can pay just as easily as a local resident. Such gateways act as a translation layer, interpreting various payment protocols and currencies in real-time to ensure that both the buyer and the seller experience a smooth, instantaneous transaction.
Simultaneously, the integration of QR and NFC technologies is breaking down the regional silos that once dictated how people paid for goods and services. Solutions that allow travelers from QR-centric markets to interact with NFC-centric infrastructure in the United States and Europe are becoming increasingly common, reducing the technical friction that once defined international travel. Moreover, the rise of super apps in regions like Thailand, Malaysia, and China has demonstrated the power of integrating travel booking, restaurant reservations, and loyalty rewards into a single, high-frequency digital ecosystem. These platforms move beyond the transactional nature of a wallet, becoming lifestyle companions that manage the entire journey, thereby increasing user stickiness and providing a template for how commerce will be conducted globally in the coming years.
Industry Perspectives on Infrastructure and Trust
The interoperability mandate has become a central theme for experts at organizations like S&P Global and Ant International, who argue that the future of commerce hinges on the ability of disparate systems to function as one. They emphasize that for a borderless economy to exist, a unified gateway is necessary to empower small local merchants who lack the resources to manage dozens of different payment integrations. Without such a gateway, the digitalization gap will only widen, leaving small-scale entrepreneurs behind as the world accelerates toward more complex digital solutions. The industry is currently focused on creating a “plug-and-play” environment where any wallet, regardless of its origin, can be accepted anywhere, thereby democratizing access to global tourism revenue for even the most remote local businesses.
Despite these technical strides, a significant trust deficit regarding artificial intelligence remains a formidable barrier to the widespread adoption of automated commerce. While 81.3% of consumers are comfortable using AI for the research and planning stages of their trips, only 26% are currently willing to trust these systems to execute actual financial transactions on their behalf. This psychological barrier is rooted in concerns over data privacy and the fear of errors that could lead to financial loss or the mismanagement of sensitive information. Industry leaders recognize that addressing this trust gap is just as important as building the underlying technology. They must implement more robust security measures and provide greater transparency in how AI makes decisions to convince a skeptical public that an algorithm can handle their money as safely as a human teller.
Regional variations in consumer expectations further complicate the global rollout of these integrated systems. While many Asian markets prioritize an all-in-one lifestyle experience where every need is met within a single application, Western consumers in markets like Germany and Japan often place a higher premium on privacy and the predictability of the payment process. These cultural nuances mean that a one-size-fits-all approach is unlikely to succeed. Instead, developers must tailor their platforms to respect local preferences for data sovereignty while still providing the convenience of international interoperability. This dual requirement for global scale and local customization is the primary challenge facing the next generation of commerce infrastructure, requiring a sophisticated balance of technology and cultural awareness.
The Future of Agentic Commerce and AI Integration
The transition toward agentic AI represents a fundamental shift in how consumers interact with the digital world, moving beyond simple chatbots to protocols that can act independently. This next phase involves Agentic Mobile Protocols where AI agents are empowered to handle complex tasks like re-bookings, refunds, and real-time navigation without constant human intervention. For instance, if a flight is delayed, an agentic wallet could automatically re-book local transportation and notify the hotel, settling any price differences autonomously. This level of agency transforms the digital wallet from a passive tool into a proactive partner, drastically reducing the mental load on the traveler and ensuring that disruptions are managed with minimal effort.
Overcoming the AI paradox is the current priority for developers who seek to move these tools from the laboratory to the marketplace. While 86% of consumers express interest in AI-supported payments, they only do so on the condition that these services are embedded within a secure and trusted ecosystem. The industry is currently working to scale technical infrastructure, such as the Super App Engine, which allows wallet partners to evolve into AI-native platforms capable of providing sophisticated, agentic services. These frameworks are designed to be privacy-first, ensuring that the automation of commerce does not come at the expense of personal security. As these systems become more refined, the expectation is that the percentage of users willing to delegate financial execution to AI will rise significantly, provided that the security outcomes remain consistently positive.
The long-term vision for a borderless economy suggests a world where the steps of discovery and execution are no longer separate, fragmented experiences. In this future, the journey is managed by a trusted digital agent that handles every detail from the initial inspiration to the final transaction at a local market. This borderless vision relies on the successful integration of AI agents with global payment gateways, creating a single, frictionless journey for every consumer. However, the industry must still navigate strict global regulatory standards and the technical challenge of maintaining privacy across various jurisdictions. The ability to harmonize these competing demands will determine whether agentic commerce remains a niche convenience or becomes the new global standard for how humans exchange value in an increasingly connected world.
Conclusion: Closing the Digitalization Gap
The shift toward hyper-local spending and the simultaneous rise of integrated digital ecosystems necessitated a move away from the fragmented, localized payment systems that once dominated the market. Industry stakeholders recognized that the survival of small-scale merchants and the satisfaction of international travelers depended entirely on a new level of technical harmony. By examining the statistics of the past year, it was clear that the demand for a unified experience had outpaced the existing infrastructure, forcing a rapid evolution in how payment gateways were designed and deployed. This period was marked by a concerted effort to bridge the gap between the QR-code economies of the East and the NFC-reliant structures of the West, ensuring that no consumer was left behind due to their choice of hardware.
Success in this era was defined by the successful implementation of interoperability and the ability of major platforms to transform AI into a trusted execution partner rather than a mere search tool. The introduction of agentic protocols allowed for a significant reduction in transaction friction, moving the industry toward a model where the digital wallet took on the responsibilities of a travel concierge. To fully realize this potential, businesses and regulators had to prioritize the development of a connected, transparent, and secure global infrastructure. This effort empowered both the modern traveler and the local merchant, creating a more inclusive economic environment where the benefits of global connectivity were felt at every level of the supply chain. Moving forward, the focus was firmly placed on maintaining this infrastructure to support a truly borderless and intelligent global economy.