

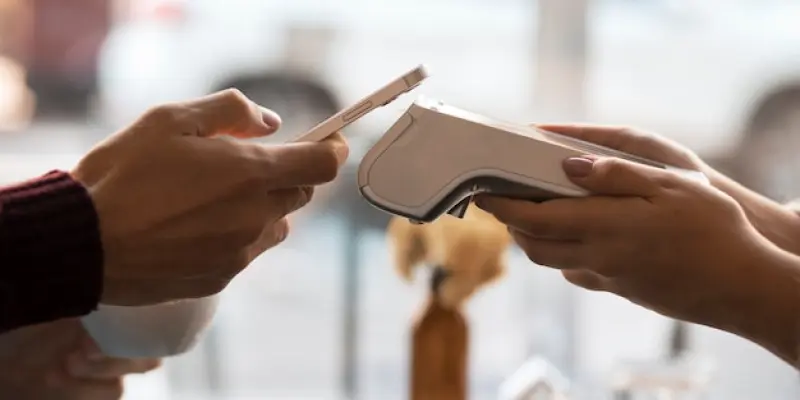
How often do people use cash these days? This question might seem almost outdated as digital payments have become the norm, transforming how society handles money. The ease and efficiency of cashless transactions are appealing, but it’s essential to understand both the benefits and challenges of this monumental shift.
A Transformation in How We Pay
From local coffee shops to major retailers, digital payments are ubiquitous, transforming the way transactions occur. Picture a typical day where payments are made using a smartphone or a smartwatch. The seamless integration of digital wallets like Apple Pay and Google Pay into daily life is evident. This scenario encourages reflection on how deeply digital payments have become embedded in everyday routines.
Why Digital Payments Matter
The significance of digital payments in today’s economy cannot be overstated. The COVID-19 pandemic played a crucial role in accelerating this transition as contactless transactions became a necessity. Coupled with rapid technological advancements, digital payments have reshaped consumer behavior, offering a glimpse into a future where physical cash might become obsolete. These shifts are not just convenient but also reflect broader trends in global economies.
The Benefits of Going Cashless
Consumer Convenience and Speed
Digital wallets have profoundly simplified the act of paying for goods and services. No more fumbling for cash or waiting for change; transactions are instantaneous. This convenience extends to features like splitting bills with friends through apps like Venmo, making financial management more accessible and efficient.
Enhanced Security and Fraud Prevention
Beyond convenience, digital payments offer enhanced security. The encryption and transaction tracking embedded in these systems reduce fraud risks. Each transaction leaves a digital trace, making it easier to track and prevent unauthorized activities, which provides an added layer of safety for users.
Operational Efficiency for Businesses
For businesses, the benefits are substantial. Digital payments streamline operations by minimizing the need for cash handling, which in turn reduces the risks associated with theft. They also facilitate better record-keeping and inventory management, allowing businesses to focus on growth and customer satisfaction.
Challenges in Adopting Cashless Payments
Privacy and Data Security Concerns
Despite the benefits, there are significant concerns about privacy and data security. Each digital transaction generates data that could be accessed by banks, tech companies, or even government entities, raising fears about surveillance and data breaches. Ensuring that this data remains secure is a critical challenge.
Financial Inclusion and Accessibility
Another significant concern is the exclusion of “unbanked” or “underbanked” populations. Many individuals still lack access to traditional banking services and digital payment options. The risk of further marginalizing these groups in a cashless society is real and cannot be ignored. Finding solutions to include everyone in the financial ecosystem is paramount.
Global Case Studies: Lessons Learned
Sweden as a Pioneer
Sweden’s transition to a cashless society offers valuable insights. The efforts by the Riksbank, Sweden’s central bank, to promote digital payments have led to a society where cash is rarely used. This model shows both the possibilities and the potential pitfalls of a fully digital economy.
India’s Financial Inclusion Initiatives
Conversely, India has focused on bringing digital payments to rural and underserved areas. Through various government initiatives, the country aims to ensure that digital payments reach even the most remote communities. These efforts highlight the importance of inclusive strategies in transitioning to a cashless economy.
Expert Insights and Research
According to industry experts and economists, the future of digital payments holds great promise but also significant risks. For instance, Caroline Casey, a leading economist, suggests, “The strides in digital payments could very well redefine economies, but it is important to address privacy concerns and ensure no one is left behind in this digital shift.” Research from financial institutions underscores the necessity of robust data security measures and inclusive financial policies.
Practical Steps for Navigating a Cashless Future
Adopting Digital Payment Solutions Safely
For individuals and businesses, safeguarding data privacy is crucial. Using strong, unique passwords for digital wallets, enabling two-factor authentication, and staying vigilant against phishing scams are key steps to secure digital transactions.
Ensuring Financial Inclusion
Policymakers and organizations must work together to guarantee that digital payment systems are accessible to all. Initiatives aimed at increasing digital literacy and providing affordable access to banking services are essential to prevent exclusion in a cashless society.
Ultimately, the shift toward a cashless economy presents an array of benefits and challenges. It is a future filled with promise for efficiency, security, and convenience but requires careful consideration to ensure inclusivity and data protection. As societies continue to embrace digital payments, the focus must be on creating systems that are secure, equitable, and accessible to everyone.