

Transaction costs on the Solana network average approximately $0.00025 per transfer, representing a drastic reduction compared to the percentages taken by legacy credit card networks. In 2026, the global payment landscape continues to evolve as merchants seek more direct ways to interact with their customers and manage their capital. The traditional financial system, built on layers of intermediaries, often subjects businesses to delays and high fees that can stifle growth. Solana Pay emerged as a solution to these persistent issues by leveraging a high-performance blockchain to facilitate peer-to-peer transfers. This system is not merely a tool for digital enthusiasts but a comprehensive framework designed for mainstream commerce. By removing the middlemen and settling transactions in real-time, it offers a level of efficiency that was previously unattainable. As businesses look toward the future, the integration of these protocols marks a significant step in the modernization of the global retail and financial services sectors.
1. The Core Architecture: Defining and Processing Digital Payments
Solana Pay is an open-source payment framework and developer kit meticulously engineered to sit atop the Solana blockchain. It allows businesses of any size to accept digital dollars, specifically USDC, and other specialized tokens directly from their customers. The development of this protocol was the result of a collaborative effort involving Solana Labs, Circle, and several prominent financial technology leaders. By bypassing the intricate web of traditional banking networks, Solana Pay settles transactions directly on-chain, ensuring that the merchant retains a higher portion of the sale. This decentralized architecture eliminates the need for clearinghouses or third-party payment processors that typically introduce latency and additional costs. In 2026, the protocol continues to serve as a bridge between the traditional retail world and the growing digital asset economy, providing the technical infrastructure required for secure and verifiable peer-to-peer transfers on a global scale.
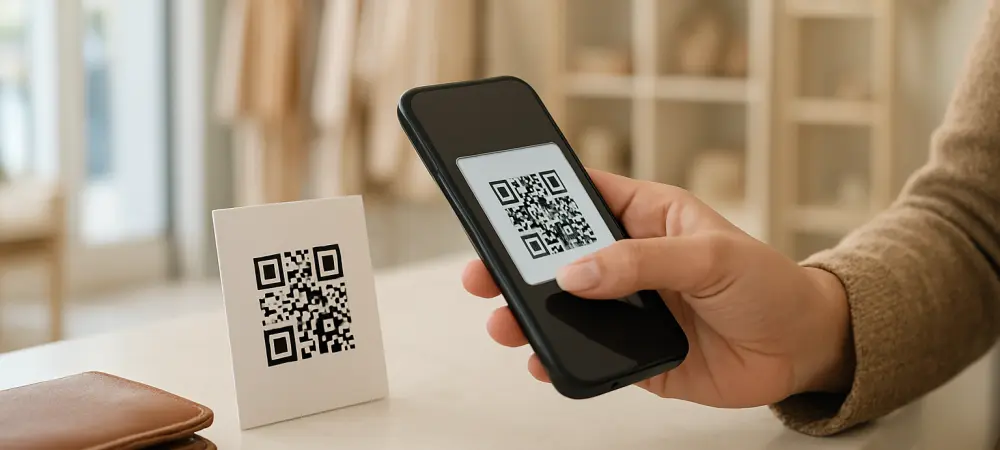
The operational flow of the system functions as a direct digital interaction between a storefront and a user’s crypto wallet, characterized by four distinct phases. First, the seller generates a specific transaction request, which is typically presented as a dynamic QR code at the point of sale or within a digital checkout interface. Second, the buyer scans this code using a compatible Solana-based mobile wallet and confirms the payment details with a simple biometric or passcode authentication. Third, the transfer is finalized on the blockchain in a matter of seconds, leveraging Solana’s unique consensus mechanism to achieve near-instant finality. Finally, both the merchant and the customer receive an immediate notification that the payment was successful, allowing the goods or services to be released without waiting for a multi-day settlement cycle. This streamlined process removes the uncertainty often associated with legacy electronic payments, where transactions can be reversed long after the initial sale occurs.
2. Economic Efficiency: Advantages and Platform Integrations
One of the primary drivers of adoption for this protocol is the combined advantage of minimal overhead and extreme operational efficiency. While traditional credit card processors often take a percentage of every sale in addition to flat per-transaction fees, Solana Pay maintains a cost structure that is virtually negligible. These savings directly impact the bottom line for high-volume retailers and small businesses alike, who have long struggled with the erosion of margins caused by legacy financial rails. Furthermore, the speed of settlement represents a massive improvement over traditional bank transfers that can take several business days to clear. In the current 2026 economic environment, having immediate access to liquidity is a significant competitive advantage for merchants who need to manage inventory or payroll in real-time. By providing millisecond settlement times, the network ensures that a business’s capital is never trapped in a “pending” state, allowing for more dynamic and responsive financial management.
The reach of Solana Pay expanded significantly following its integration as an officially approved application on Shopify, one of the world’s largest e-commerce platforms. This partnership enabled millions of online retailers to incorporate blockchain-based payments into their existing storefronts with minimal technical configuration. For these merchants, the ability to accept stablecoins like USDC alongside traditional currency has opened up new customer segments, particularly among younger, tech-savvy demographics. The integration was designed to feel familiar to both the merchant and the end-user, ensuring that the transition to digital asset payments does not disrupt the established user experience. Customers can choose to pay with their digital wallets just as easily as they would select a credit card, while merchants benefit from the immediate finality and lack of chargeback risk. This move signaled a major step toward the mainstreaming of blockchain technology within the global retail ecosystem.
3. Strategic Evolution: Innovation, Risks, and Outcomes
Beyond its role as a simple processing tool, the protocol introduces innovative features that allow for a deeper direct link between merchants and their customers. By interacting directly with a user’s wallet, businesses can implement unique engagement strategies that were previously impossible with traditional payment systems. For example, some retailers have introduced restricted access offers, where specific discounts or products are only available to customers holding certain digital assets. Others have developed digital loyalty programs based on NFTs, providing personal rewards that are easily verifiable and transferable. Merchants also utilized the direct connection to send promotional materials and specialized tokens straight to a user’s wallet address, creating a more interactive relationship. Additionally, the sustained growth of the Solana ecosystem has been supported by significant institutional adoption from giants like Visa and PayPal, who utilized the network for cross-border payroll solutions.
Despite the clear advantages, implementing a blockchain-based payment system required careful consideration of potential hurdles and technical risks. Businesses had to account for the fact that user adoption remains a significant factor, as many customers are still in the process of becoming comfortable with managing digital wallets and private keys. Furthermore, any integration with a blockchain network carries inherent technical risks, such as the possibility of coding errors in smart contracts or occasional network interruptions. Merchants often spent time monitoring the broader health of the ecosystem and tracking token prices to gauge the platform’s overall stability and activity levels. Staying informed about protocol upgrades and security best practices was essential for maintaining a secure payment environment. While these challenges were manageable, they required a proactive approach to risk management and a commitment to ongoing education for both staff members and the customer base.
Strategic leaders successfully navigated the transition to blockchain commerce by focusing on long-term infrastructure over short-term trends. Organizations that integrated Solana Pay early benefited from a streamlined treasury process and reduced reliance on expensive intermediaries. These businesses implemented comprehensive training programs to familiarize their teams with wallet management and digital asset security. Furthermore, they established clear protocols for converting stablecoins into local currencies to manage tax obligations and operational expenses. By monitoring the ongoing developments within the Solana ecosystem from 2026 to 2028, merchants stayed ahead of the curve regarding new features like automated recurring payments. The adoption of these tools allowed companies to reclaim a significant portion of their revenue that was previously lost to transaction fees. Ultimately, the shift toward direct, on-chain payments proved to be a decisive factor in improving merchant profitability across diverse global markets.