

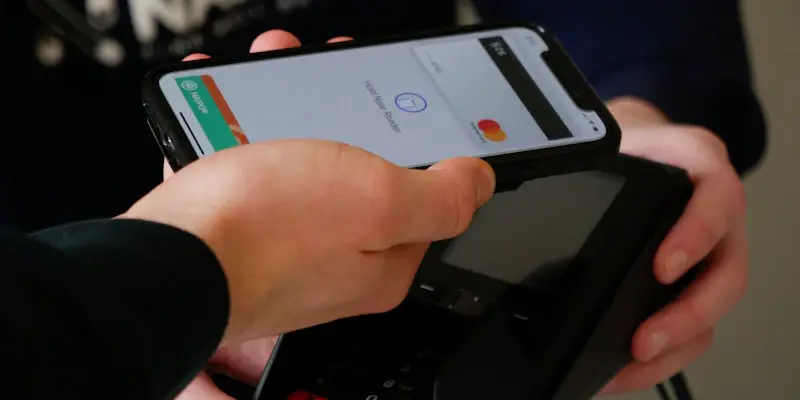
The rise of digital wallets like Apple Pay and Google Pay has revolutionized the way consumers handle transactions. These tech-driven solutions offer convenience and speed, but they also raise questions about regulatory oversight. A coalition of tech companies, led by giants such as Apple and Google, is currently challenging the Consumer Financial Protection Bureau (CFPB) over its attempt to regulate digital wallets similarly to traditional payment firms. This legal battle underscores a broader debate about the appropriate level of regulation for these innovative financial tools.
The CFPB’s New Rule and Its Implications
In November, the CFPB finalized a rule that took effect on January 9, mandating that providers of digital wallets and payment apps processing over 50 million transactions annually be subject to the agency’s supervision. This includes oversight of their use of consumer data, handling of fraud and complaints, and procedures around account shutdowns. The CFPB argues that this supervision is essential to protect consumers in an increasingly digital financial landscape.
Tech companies, however, contend that digital wallets merely transmit payment credentials, such as a consumer’s credit card information, to facilitate purchases from merchants. They argue that this function is fundamentally different from directly processing funds, which should exempt them from the same level of regulation as traditional payment firms. This distinction is at the heart of the lawsuit filed by TechNet and NetChoice on January 16. The tech firms assert that the CFPB is overstepping its legal boundaries by imposing regulations meant for entities that handle actual transfers of money.
The CFPB believes that robust oversight is crucial to protect consumers who increasingly rely on digital wallets and payment apps for electronic fund transfers. The bureau emphasizes that without proper regulation, consumers could face significant vulnerabilities, including security threats and account access issues. The November 21 news release from the CFPB highlighted the rapid emergence of risks in the digital wallet market, reinforcing the need for proactive supervision to manage these risks effectively.
The Tech Industry’s Argument
The coalition of tech companies asserts that the CFPB has misclassified digital wallets by conflating their role with that of direct payment services. They argue that digital wallets do not handle payments for goods and services directly but instead act as intermediaries that transmit payment information. This, they believe, should place them outside the scope of the CFPB’s intensified regulations. The distinction they make is that digital wallets merely facilitate transactions without actually processing the funds themselves.
Ramnath Chellappa, a professor specializing in Information Systems & Operations Management, supports this view to some extent. He acknowledges that digital wallets function differently from systems that store funds and directly transfer money. However, he also points out that tech companies still have obligations to consumers, particularly regarding security and account access. The potential vulnerabilities, such as hacking risks and the ability of companies like Apple and Google to shut users out of accounts, indicate that some form of regulatory oversight remains necessary, even if the specifics of the CFPB’s rule might be up for debate.
Despite this nuanced understanding, the tech companies’ argument centers on the belief that their digital wallets should not be regulated in the same way as traditional payment firms. They see the CFPB’s move as an overreach, characterizing it as an effort by CFPB Director Rohit Chopra to target large technology firms. The lawsuit filed by TechNet and NetChoice aims to prevent what they perceive as an undue extension of regulatory power over digital wallet providers.
Consumer Advocacy Perspective
From a consumer advocacy standpoint, organizations argue that tech companies are attempting to sidestep regulation through semantic distinctions. Adam Rust, Director of Financial Services for the Consumer Federation of America, interprets the tech firms’ complaint as an effort to avoid responsibility. He emphasizes that digital wallets facilitate electronic funds transfers, which can pose significant risks to consumers if not properly regulated. Consumer advocates argue that the role of digital wallets in facilitating such transfers warrants stringent oversight.
Consumer advocates stress the importance of stringent oversight due to potential consumer harms, such as losing access to accounts without notice or disrupted payment capabilities. They argue that the CFPB’s rule is necessary to ensure that digital wallet providers are held accountable for their role in the financial ecosystem. The oversight is seen as vital to protect consumers from potential issues that could arise from the widespread use of digital wallets, including security breaches and other vulnerabilities.
The CFPB argues that technology companies should have equal obligations under consumer protection laws as traditional payment companies. The bureau’s stance is that the authority to regulate these companies has always been within its purview, and the interpretive rule merely formalizes this power. Proactive supervision is deemed essential by the CFPB to assess and manage the risks associated with digital wallets and payment apps effectively.
The Broader Debate on Tech Regulation
The emergence of digital wallets like Apple Pay and Google Pay has completely changed how people manage their transactions. These technologically advanced solutions bring unmatched convenience and speed to consumers. However, they also bring up important regulatory oversight questions. Currently, a coalition of tech companies, including powerhouses such as Apple and Google, is disputing the Consumer Financial Protection Bureau’s (CFPB) effort to impose regulations similar to those on traditional payment firms on digital wallets. This legal dispute highlights a much larger discussion about the suitable level of regulation for these new financial tools. Are digital wallets to be treated the same as traditional payment systems, or do they require a different approach? This question is vital as digital wallets continue to grow in popularity, making it crucial to find a balance between fostering innovation and protecting consumers. The ongoing debate indicates that as technology evolves, so must the frameworks that govern its use.