

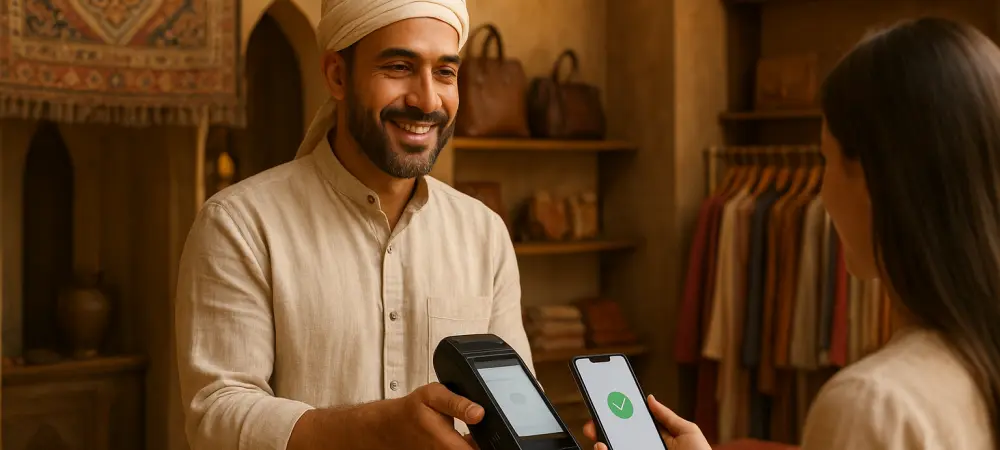
The rapid shift toward digital finance in the United Arab Emirates and Egypt is fundamentally altering how enterprises manage their daily cash flow and corporate expenditures. This transition is not merely a convenience but a strategic necessity for businesses looking to thrive in a landscape where speed and transparency are paramount. Traditionally, companies across the Middle East have struggled with the inefficiencies of legacy banking systems that required multiple platforms for different financial tasks. The partnership between Mastercard and Arab Financial Services addresses these pain points by offering a unified digital ecosystem that streamlines everything from B2B payments to real-time expense tracking. This shift is particularly evident in the way that corporations are now prioritizing automated reconciliation over manual entry, reducing human error and freeing up valuable resources for more strategic initiatives. As businesses embrace these tools, the entire financial infrastructure of the region is undergoing a profound and necessary modernization.
Strengthening Regional Infrastructure: Strategic Reach and Local Trust
Building on this foundation, the collaboration leverages the immense technical infrastructure of Mastercard alongside the localized expertise of Arab Financial Services. As a provider that is majority-owned by thirty-six different financial institutions throughout the region, AFS possesses an inherent level of institutional trust that few global competitors can replicate. This ownership structure provides a unique distribution advantage, allowing for the rapid deployment of new technologies across a wide network of partner banks. Mastercard provides the global payment rails and security protocols that ensure these transactions are safe and recognized worldwide, creating a powerful synergy between global scale and local relevance. This approach is specifically tailored to the nuances of the Middle Eastern market, where regulatory compliance and regional relationships are critical to long-term success. The resulting framework offers a robust alternative to the fragmented systems of the past, ensuring that enterprises can scale with confidence.
The rollout strategy focuses on the United Arab Emirates and Egypt, two markets that represent the vanguard of digital adoption in the region. In the UAE, which serves as a global hub for financial technology, the appetite for sophisticated payment solutions is higher than ever. Meanwhile, Egypt represents a massive opportunity for growth, as its government actively pursues financial inclusion and a transition away from a cash-dependent economy. By targeting these specific geographies, the partnership is able to capitalize on diverse economic drivers, from the high-tech corporate environments of Dubai to the rapidly expanding entrepreneurial sector in Cairo. This geographic focus ensures that the solutions provided are not only technically sound but also culturally and economically aligned with the needs of the local business community. The ability to navigate these distinct markets with a single, cohesive strategy is what sets this initiative apart from broader expansions. This targeted entry ensures that the digital tools reach the organizations that need them the most.
Enhancing Corporate Spend: A New Standard for Payment Acceptance
Central to this transformation is the AFS Pro platform, which acts as a comprehensive command center for corporate financial activities. On the payables side, the application empowers finance departments with an unprecedented level of granular control over how and where funds are spent. Rather than relying on outdated physical processes, teams can now issue virtual and physical corporate cards instantly, assigning specific spending limits and usage categories for individual employees. This real-time visibility into company expenditures allows for immediate budget adjustments and prevents the common problem of end-of-month accounting surprises. The integration of sophisticated expense reconciliation tools directly within the app means that receipts and transaction data are matched automatically, significantly reducing the administrative burden on treasury teams. This move toward agile financial management allows businesses to respond more quickly to market opportunities while maintaining strict oversight of their internal resources. It represents a significant leap forward.
On the receivables side of the equation, the platform introduces groundbreaking technology that simplifies how businesses collect payments from their customers. The SoftPOS functionality is a game-changer, as it allows any NFC-enabled smartphone to function as a professional point-of-sale terminal without the need for expensive or bulky hardware. This is particularly beneficial for small businesses and mobile service providers that require a flexible and cost-effective way to accept contactless payments. Furthermore, the inclusion of Pay-by-Link capabilities enables enterprises to facilitate remote transactions through simple digital links sent via messaging apps or email. By housing these acceptance tools alongside a data-rich business dashboard, the partnership provides a business-in-a-box solution that allows owners to monitor their sales performance and cash flow in one place. This integration of payables and receivables into a single application effectively closes the loop on corporate financial cycles, making it easier for businesses to manage their liquidity.
Navigating Economic Shifts: Regulatory Alignment and Scalable Models
The expansion of these digital tools is occurring within a highly supportive regulatory framework that prioritizes the modernization of financial services. In the United Arab Emirates and Egypt, central banks have implemented forward-thinking regulations that encourage fintech innovation while maintaining high standards of security. These policies have created an environment where companies can adopt new payment models like the Banking-as-a-Service system. This model allows other financial institutions to utilize the AFS Pro infrastructure as a white-label solution, enabling smaller banks to offer high-quality corporate payment products without the massive costs of developing proprietary technology. This collaborative approach is essential in markets where the banking sector remains relatively fragmented. By providing a standardized framework, the partnership between Mastercard and AFS accelerates the pace of digital adoption and ensures a level of consistency that benefits the entire ecosystem, fostering growth.
In conclusion, the partnership between Mastercard and Arab Financial Services provided a definitive roadmap for the digital transformation of corporate payments in the region. The decision to integrate payables and receivables into a single ecosystem proved to be the most significant structural innovation, as it addressed the primary pain points of administrative overhead and fragmented data. Furthermore, the strategic alignment with the central banks of the UAE and Egypt ensured that the platform remained a stable and trusted pillar of the emerging digital economy. Businesses that adopted these tools reported a significant reduction in transaction costs and a marked improvement in cash flow visibility. Looking forward, enterprises should continue to prioritize the adoption of unified payment platforms to stay competitive. The foundation established by this collaboration suggested that the future of regional commerce would be defined by seamless, secure, and digitally-driven financial interactions.