

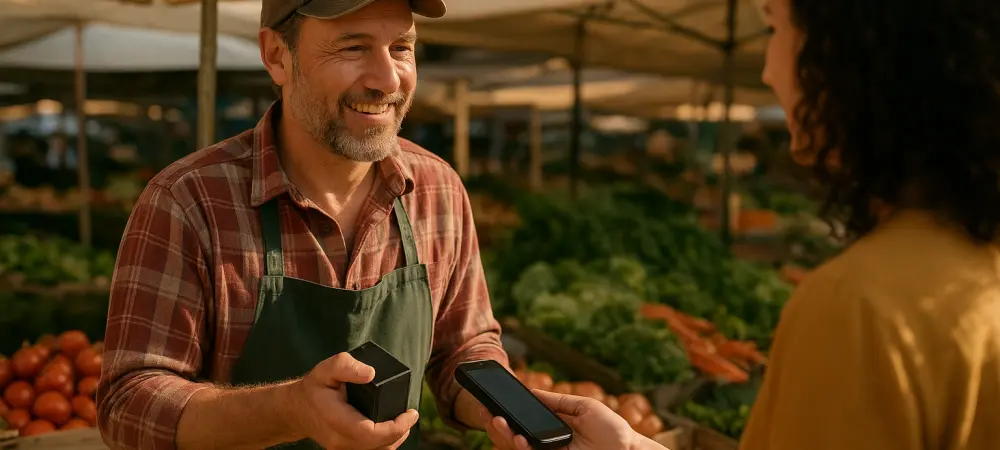
The rapid evolution of mobile technology in Eswatini has transformed how residents approach daily financial tasks, moving away from the limitations of physical currency. Beyond physical retail outlets, e-Mali supports digital payments for online stores and ticketing services to accommodate the growing demand for e-commerce in Eswatini. This platform, developed by Eswatini Mobile, functions as a comprehensive digital wallet that integrates seamlessly with the existing telecommunications infrastructure. By offering a simplified user interface accessible via both smartphones and basic feature phones, the service has successfully reached segments of the population that were previously underserved by the traditional banking sector. The initiative represents a critical pillar in the national strategy to digitize the economy, ensuring that financial services are not a luxury reserved for the urban elite. As the ecosystem expands, the focus remains on creating a frictionless experience that encourages users to transition from cash-heavy habits to secure, digital-first alternatives that provide greater flexibility and control.
1. Expanding the Scope of Financial Inclusion
One of the primary drivers behind the success of this digital payment system is its commitment to expanding the scope of financial inclusion across the kingdom. By leveraging the ubiquity of mobile devices, the service allows individuals to perform transfers, pay bills, and manage savings without the prerequisite of a traditional bank account. This is particularly impactful for the informal sector, where street vendors and small-scale farmers often struggle to access formal financial institutions. The system provides these users with a secure digital record of their transactions, which can eventually serve as a basis for building credit profiles. From 2026 to 2028, the platform is expected to introduce more sophisticated micro-loan and insurance products, further empowering the local workforce. This strategic focus on accessibility ensures that no citizen is left behind as the country moves toward a more digitized landscape, fostering a sense of financial independence that is essential for sustainable and inclusive growth.
Furthermore, the integration of these digital tools into the daily operations of local businesses has created a more dynamic and resilient marketplace. Merchants who previously relied solely on cash transactions now utilize mobile money to streamline their accounting and reduce the overhead costs associated with physical money management. This shift has not only improved operational efficiency but has also enhanced customer safety by minimizing the need for people to carry large sums of money. The platform facilitates real-time settlements, allowing business owners to reinvest their earnings immediately rather than waiting for lengthy bank processing cycles. As more enterprises adopt these digital solutions, the entire economic value chain becomes more transparent and efficient. This creates a ripple effect where increased merchant participation leads to higher consumer confidence, eventually resulting in a self-sustaining cycle of digital adoption. The ease of use and low barrier to entry remain the key factors in convincing skeptical traditionalists to make the switch.
2. Enhancing Transactional Security and User Trust
Addressing the inherent risks of digital finance is a top priority for the developers, who have implemented high-level security protocols to protect user data and funds. Advanced encryption techniques and multi-factor authentication are standard features designed to prevent unauthorized access and mitigate the threat of cybercrime. These measures are critical in an era where digital fraud is becoming increasingly sophisticated, requiring constant vigilance and frequent updates to the underlying software. The platform also employs real-time monitoring systems that can detect and flag suspicious activities before they impact the user. This proactive approach to security is vital for maintaining the trust of the public, especially as larger portions of the population migrate their primary financial activities to the mobile network. By ensuring that every transaction is encrypted and verified, the service provides a level of protection that often exceeds that of traditional cash transactions, which are susceptible to physical loss.
Compliance with national and international financial regulations also plays a significant role in the platform’s operational strategy. By working closely with the Central Bank of Eswatini, the service ensures that all its offerings align with current anti-money laundering and know-your-customer standards. This collaboration helps to legitimize mobile money as a serious alternative to traditional banking and provides a layer of institutional oversight that protects the broader economy. From 2026 to 2029, the regulatory environment is likely to evolve further, requiring the platform to adapt its technological infrastructure to meet new transparency requirements. These efforts are not merely about following rules; they are about establishing Eswatini as a forward-thinking hub for fintech innovation in the Southern African region. When users know that their digital wallet is recognized and regulated by the state, they are more likely to commit to long-term usage, which in turn provides the data necessary for the government to track trends.
3. Driving Economic Growth Through Digital Innovation
The future of digital payments in the kingdom is closely tied to the concept of interoperability, where different financial systems can communicate and exchange value seamlessly. Efforts are already underway to ensure that users can transfer funds not only within the same network but also across different mobile operators and traditional banks. This cross-platform compatibility is essential for reducing the fragmentation that often hinders the growth of digital ecosystems. By breaking down the silos between different providers, the platform becomes more useful for the average consumer who may need to interact with various entities daily. In the coming years, starting from 2026, the focus will shift toward expanding these capabilities to include international remittances, allowing the Eswatini diaspora to send money home with lower fees and faster processing times. Such innovations will further cement the role of mobile finance as the primary engine for economic connectivity, bridging the gap between local aspirations and the global economy.
The implementation of these features provided a robust framework for financial autonomy across the kingdom. Stakeholders observed that early adopters who integrated these systems into their daily operations gained a competitive advantage in the local market. Moving forward, businesses prioritized the adoption of multi-platform payment gateways to ensure they met the evolving expectations of a tech-savvy consumer base. This transition effectively eliminated the barriers between digital wallets and traditional commerce, setting a new standard for regional financial services. Organizations that maintained agility in their digital strategy successfully mitigated the disruptions previously caused by cash shortages. The lessons learned from this rollout suggested that continuous investment in user education and infrastructure remained the most viable path toward long-term economic stability. Consequently, the focus shifted toward refining cross-border capabilities to further enhance the utility of the mobile money ecosystem for every citizen who sought a modern way to manage wealth.