

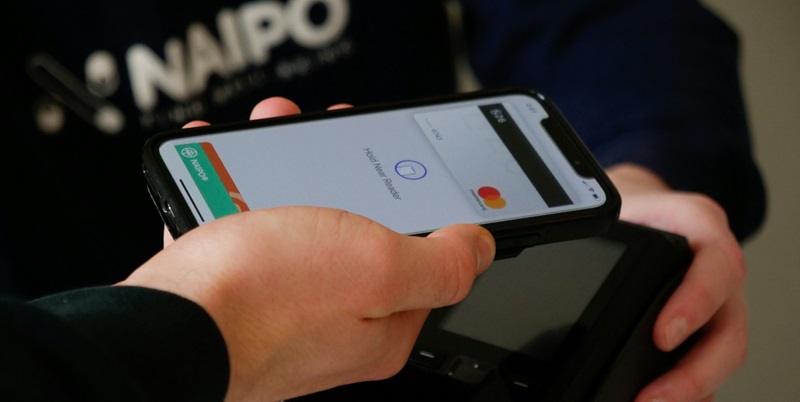
As we progress through an age of rapid technological progress, global payment systems are on the cusp of major changes. The advent of mobile payment platforms, the emergence of digital currencies, and the innovative use of blockchain are at the forefront of reshaping finance. Each innovation, while promising to simplify transactions, raises significant security issues that cannot be ignored.
Regulatory bodies around the world now face a complex task: they must encourage technological growth while also safeguarding the financial system’s security and robustness. Striking the right equilibrium here is vital. The stakes are high, as the outcomes will directly impact consumer safety, ensure fair market practices, and bolster defenses against financial crimes. Such a balance will be paramount in charting the course for a financial ecosystem that is both innovative and secure.
Fostering Innovation in Payment Systems
Encouraging innovation in payment methods is vital for enhancing efficiency, lowering costs, and providing greater access to financial services. New technologies have the ability to leapfrog traditional infrastructure bottlenecks, making it possible to reach unbanked and underbanked populations. However, regulators are tasked with a difficult mandate: to promote such technological advances while simultaneously erecting a robust framework that can avert potential risks to consumers and the financial system. The key question for regulators is how to formulate policy that is sufficiently flexible to accommodate rapid technological changes without becoming obsolete or stifling progress.
The process of framing regulations for novel payment systems must be approached with a careful blend of foresight and adaptability. External consultations, periodic reviews, and feedback loops with innovators can help regulators understand the implications of emerging technologies and update regulatory frameworks accordingly. Yet, the pace at which innovations emerge sometimes outstrips the ability of regulatory bodies to keep up, thus necessitating a more proactive and forward-thinking approach. Incorporating principles-based rather than rules-based regulation can offer the latitude needed for emerging technologies to develop, while maintaining the core objectives of consumer protection and financial stability.
Upholding Security and Consumer Protection
With financial innovation comes the risk of security threats such as data breaches and fraud. Regulators are tackling these issues by implementing stringent authentication protocols, real-time monitoring systems, and encrypted channels to protect users. Educating consumers about how to safely use digital payments is also crucial for a secure financial ecosystem.
Moreover, regulatory bodies are ensuring consumer protection with dispute resolution and compensation systems, which bolster trust in new payment methods. Establishing a clear framework outlining the rights and duties involved in transactions underpins this trust.
The challenge for regulators is to balance fostering payment innovation with maintaining a secure financial space. The correct measures will allow the financial industry to harmoniously blend progress with safety, propelling it into a future where advancements and security coexist, providing both growth and stability.